Dairy farming business in India continues to attract entrepreneurs in 2026 due to steady milk demand and scope for value-added products. If you know how to start a dairy farm business in India, a structured plan helps you control costs, manage animals, and grow sustainably. Many first-time founders now view the dairy farm business as a long-term enterprise rather than a side income option. With better access to dairy farming loan options and organised markets, this business in India offers stable returns when planned well.
What Is a Dairy Farm Business?
A dairy farm business refers to the rearing and management of milk-producing animals like cows and buffaloes for commercial purposes. The dairy business meaning covers the complete cycle of animal care, breeding, feeding, and milk production activities. It also includes processing and selling milk and by-products such as curd, paneer, butter, and ghee. Farmers earn income not only from fresh milk sales but also by adding value through basic processing and steady local demand.
Types of Dairy Farm Business Models
There are different dairy farm business models in India, and each works based on budget, scale, and local demand. Small-scale dairy farming suits beginners with limited investment and focuses on selling fresh milk locally. Commercial dairy farming involves a larger herd, higher investment, and bulk supply to dairies or cooperatives. Organic dairy farming targets premium customers by avoiding chemicals and using natural feed. Buffalo-only dairy farming is popular due to higher fat content and better milk prices. Value-added dairy earns more by selling paneer, curd, ghee, or butter.
|
Business Model
|
Investment Level
|
Profit Logic
|
|
Small-scale dairy
|
Low
|
Local milk sales
|
|
Commercial dairy
|
High
|
Bulk supply & volume
|
|
Organic dairy
|
Medium
|
Premium pricing
|
|
Buffalo-only dairy
|
Medium
|
High-fat milk rates
|
|
Value-added dairy
|
Medium to High
|
Higher margins
|
How to Start a Dairy Business in India?
Starting a dairy farming business in India needs proper planning and step-by-step execution. You must focus on location, animal health, and daily operations to avoid losses. Here’s a brief overview of how to start dairy farming:
- Arrange land with a proper water supply.
- Build a clean and ventilated cattle shed.
- Select suitable cow or buffalo breeds.
- Arrange licenses and basic registrations.
- Plan funding through savings or loans.
- Hire basic staff or helpers if needed.
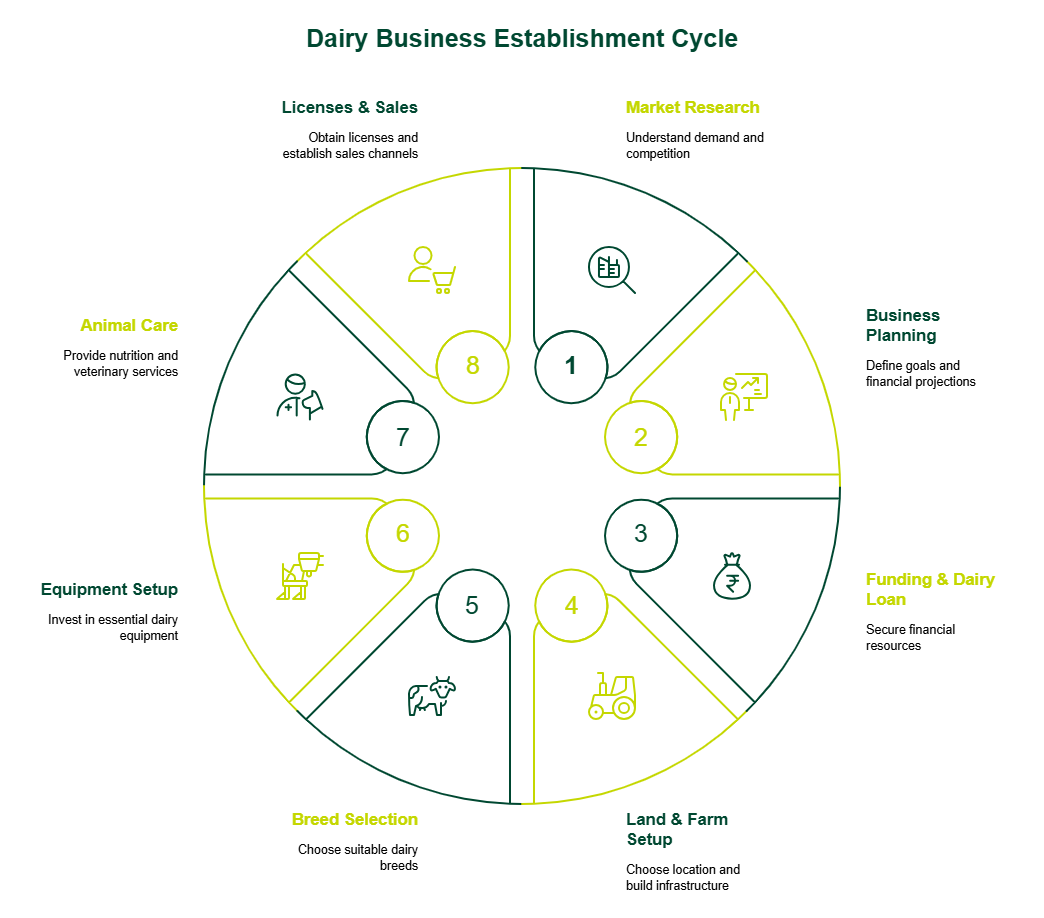
Detailed Step-by-Step Setup Process
- Market Research
Start by understanding local demand, milk pricing, and competition before entering the dairy business in India. Study whether consumers prefer cow milk or buffalo milk, average daily consumption, and existing suppliers. This helps you decide herd size, pricing strategy, and whether to focus on raw milk or value-added products.
- Planning
Create a practical dairy farm business plan that clearly outlines setup costs, monthly expenses, break-even timeline, and expected income. A written plan keeps you focused and is also required when applying for loans or government schemes.
- Funding
Explore dairy business loan* options from lenders and cooperative institutions. NABARD-linked schemes can help reduce the upfront burden. Funding is usually used for cattle purchase, shed construction, equipment, and working capital.
- Land & Layout
Finalise land with reliable water access and electricity. A proper dairy farm setup should include good drainage, airflow, and separate areas for cattle resting, feeding, and waste collection to maintain hygiene.
- Shed Construction
Follow a practical dairy shed design that keeps animals comfortable in all seasons. Adequate spacing, roofing for heat protection, and non-slippery flooring directly impact animal health and milk yield.
- Breed Selection
Choose breeds like Gir cow, Sahiwal cow, Murrah buffalo, Jersey cow, or Holstein Friesian (HF) based on milk yield, climate suitability, and feed availability. Avoid mixing too many breeds in the early stage.
- Equipment
Install essential equipment such as a chaff cutter machine, milk chilling unit, storage cans, and clean water systems to maintain milk quality and reduce spoilage.
- Feed Planning & Animal Care
Provide balanced nutrition with green fodder, dry fodder, and concentrates. Regular health check-ups through veterinary services and guidance from the Animal Husbandry Department help prevent diseases.
- Licences, Waste & Sales
Obtain the applicable licences, including the FSSAI licence and MSME registration (Udyam). Use a biogas plant for manure management and explore direct-to-consumer (D2C) milk delivery to improve margins.
How to Create a Dairy Farming Business Plan?
A structured dairy farming business plan is the foundation of a successful business in India. It helps you set clear goals, estimate costs, manage risks, and plan steady growth. A well-prepared plan is also essential when applying for a dairy farming loan or other funding support.
Start with an executive summary that explains your idea, scale, and long-term vision. Follow this with market analysis to assess local demand, pricing, and competition. The operations section should cover your dairy farm setup, breed selection, feed planning, and daily management. Include detailed financials outlining dairy farming startup costs, monthly expenses, expected revenue, and break-even point.
Finally, define your marketing strategy, including local distribution or a direct-to-consumer (D2C) model, to ensure consistent sales.
Key Components of a Dairy Farming Business Plan
A well-structured dairy farming business plan should include:
- Executive summary explaining vision and scale
- Market demand and local competition analysis
- Planned herd size and breed selection
- Shed layout and infrastructure planning
- Waste management strategy
- Financial projections and cost estimates
- Break-even timeline and profit expectations
Requirements of Dairy Farming Business Plan
To execute a dairy farming business plan, you need land, water, and proper cattle housing. Skilled labour, regular veterinary services, electricity, and transport are essential. A milk chilling unit preserves quality, while coordination with the Animal Husbandry Department ensures compliance. These requirements support stable dairy farming investment and smoother daily operations.
Infrastructure & Equipment Requirements
- Land: Sufficient space for cattle housing, feed storage, and waste management. Location should allow easy milk transport.
- Water Supply: Clean and continuous water for drinking, cleaning sheds, and equipment washing.
- Cattle: Healthy, high-yield breeds selected as per your climate and milk demand.
- Labour: Skilled or semi-skilled workers for feeding, milking, and cleaning.
- Feed and Fodder: Steady supply of green fodder, dry fodder, and concentrate feed.
- Veterinary Services: Regular health check-ups, vaccination, and emergency support.
- Electricity and Power Backup: Required for lighting, milking machines, and chilling equipment.
- Milk Chilling and Storage: Basic cooling system to maintain milk quality.
- Transport Arrangement: Quick delivery to local buyers, collection centres, or direct customers.
Tips to Start Your Own Dairy Farm Business
If you want to build a stable dairy farm business in India, focus on steady growth rather than rapid expansion. Managing risk in the early stage helps you avoid financial pressure and operational mistakes.
- Start with a manageable herd and scale gradually as you gain confidence and stable cash flow.
- Buy cattle only from certified and trusted sources to ensure good health and milk yield.
- Maintain proper hygiene in sheds, feeding areas, and during milking.
- Keep clear daily records of milk output, feed costs, and medical history.
- Ensure your animals protect your dairy farm business from unexpected losses.
- Schedule regular veterinary services to prevent disease outbreaks.
- Stay connected with the Animal Husbandry Department for guidance, vaccination drives, and long-term sustainability support.
Cost to Start a Dairy Farming Business in India
The cost to start a dairy farm business in India depends mainly on herd size, infrastructure, and location. A small dairy farming startup with around five cows or buffaloes may require an investment of ₹4 to 6 lakhs, covering cattle purchase, shed construction, and basic equipment. For a 10-animal setup, the dairy farming startup cost can range between ₹6 and 10 lakhs. Larger units with 20 animals may need ₹12 to 15 lakhs or more. Overall, dairy farming investment is influenced by breed selection, feed planning, labour availability, land costs, equipment, and milk chilling or transport arrangements.
How Can Business Loans Support Your Dairy Farming Business Plan?
Loans play an important role in expanding a dairy farm business, particularly after initial stabilisation. A dairy business loan or an MSME loan can help manage working capital requirements without depleting personal savings.
However, most lenders require at least 3 years of continuous business operations and recent profitability as part of business loan eligibility criteria. If your venture is newly established or yet to begin operations, a personal loan with a co-applicant who has a stable income may be an alternative funding option.
You can also explore funding options backed by NABARD and schemes like the Dairy Entrepreneurship Development Scheme (DEDS) to reduce the initial financial burden.
These funds can be used for:
- Purchasing high-yield cattle
- Constructing sheds and basic infrastructure
- Buying equipment such as milking machines and chilling units
- Managing working capital for feed, labour, and veterinary care
Government Subsidies & Schemes for Dairy Farming
The government supports new and existing dairy farmers through financial assistance and subsidy schemes to reduce the startup burden and improve sustainability.
- NABARD-backed schemes for dairy infrastructure and cattle purchase.
- Dairy Entrepreneurship Development Scheme (DEDS) for capital subsidy.
- State Animal Husbandry Department subsidies for breed, fodder, and equipment support.
Required Licences for Running a Dairy Business in India
To run a dairy farm business legally, you must complete basic registrations and follow local rules. Proper licences protect you from penalties and help build trust with buyers. Key requirements include:
- FSSAI license for milk processing and sales
- Local trade licence from the municipality
- MSME registration (Udyam) for small business benefits, where applicable
- Waste management compliance as per local pollution norms
Conclusion
A dairy farming business in India offers high potential income when supported by proper planning and daily discipline. If you follow a clear plan, choose suitable breeds, and invest in the right equipment, your dairy farm business can grow steadily over time. It is advisable to start small, manage your dairy farming investment carefully, and scale only when your cash flow becomes stable. With access to dairy farming loan options and government support, you can build a sustainable business that meets rising milk demand while creating long-term financial security.
For eligible enterprises with at least 3 years of continuous operations and consistent profitability over the last 2 years, SMFG India Credit offers collateral-free business loans of up to Rs. 1 crore*. You can benefit from competitive business loan interest rates and use tools such as EMI and eligibility calculators to plan repayments efficiently. Apply online with minimal business loan documents, or contact us for more details.
Please note that the costs mentioned in this article are indicative estimates. Actual investment requirements may vary depending on location, herd size, infrastructure standards, and market conditions.