What Is Sukanya Samriddhi Yojana?
Sukanya Samriddhi Yojana is a government-backed small savings scheme designed to help parents and legal guardians build a financial corpus for a girl child's future education and marriage expenses. Under this government savings scheme for a girl child, a Sukanya Samriddhi account can be opened in the name of an eligible girl, allowing regular contributions while earning government-notified interest. Also referred to as the SSY scheme or Sukanya Yojana, it encourages disciplined long-term savings and offers tax benefits subject to the prevailing provisions of the Income Tax Act.
Latest Sukanya Samriddhi Yojana Interest Rate 2026
The Sukanya Samriddhi Yojana interest rate 2026 stands at 8.2% per annum for the July-September quarter of FY 2026-27, confirmed by the Ministry of Finance. The SSY interest rate has stayed unchanged since April 2024, and the government reviews it every quarter based on bond yields and fiscal conditions.
SSY Full Form and Meaning
The SSY meaning and full form refer to the Sukanya Samriddhi Yojana. The account itself is often called a Sukanya Samriddhi Account, or simply Sukanya Yojana. SSY means a savings scheme, not a loan, not an insurance policy, and not a market-linked product. Your funds remain with the government, earning fixed interest, until your daughter needs it for college or her wedding.
Key Features of Sukanya Samriddhi Yojana
Before you open an account, it helps to see the Sukanya Samriddhi Yojana details in one place:
- You can open the account for a girl under 10 years old.
- Only a parent or legal guardian can open it on her behalf.
- The minimum deposit is Rs. 250 a year; the maximum deposit in SSY is Rs. 1.5 lakh.
- You need to deposit for 15 years from the date of opening.
- The account matures 21 years after opening, or upon the marriage of the girl child after she turns 18.
- Interest is compounded annually at the prevailing rate.
- Deposits qualify for a tax deduction under Section 80C.
- Partial withdrawal of up to 50% of the account balance is permitted for higher education after the account holder attains the age of 18 years or has passed Class 10, subject to the scheme rules.
- Premature closure is allowed only in specific situations.
- The account can be transferred between authorised banks and post offices anywhere in India.
Features at a Glance
|
Feature
|
Rule / Detail
|
|
Minimum Annual Deposit
|
Rs. 250
|
|
Sukanya Samriddhi Yojana Deposit Limit
|
Rs. 1.5 lakh maximum per year
|
|
Deposit Period
|
15 years from account opening
|
|
Maturity Period
|
21 years from account opening
|
|
Interest Rate
|
8.2% per annum (compounded annually)
|
|
Tax Benefit
|
Section 80C, up to Rs. 1.5 lakh
|
|
Partial Withdrawal
|
Up to 50% after age 18 or Class 10
|
|
Premature Closure
|
Allowed only on specific grounds
|
|
Transferability
|
Across any bank branch or post office in India
|
Benefits of Sukanya Samriddhi Yojana
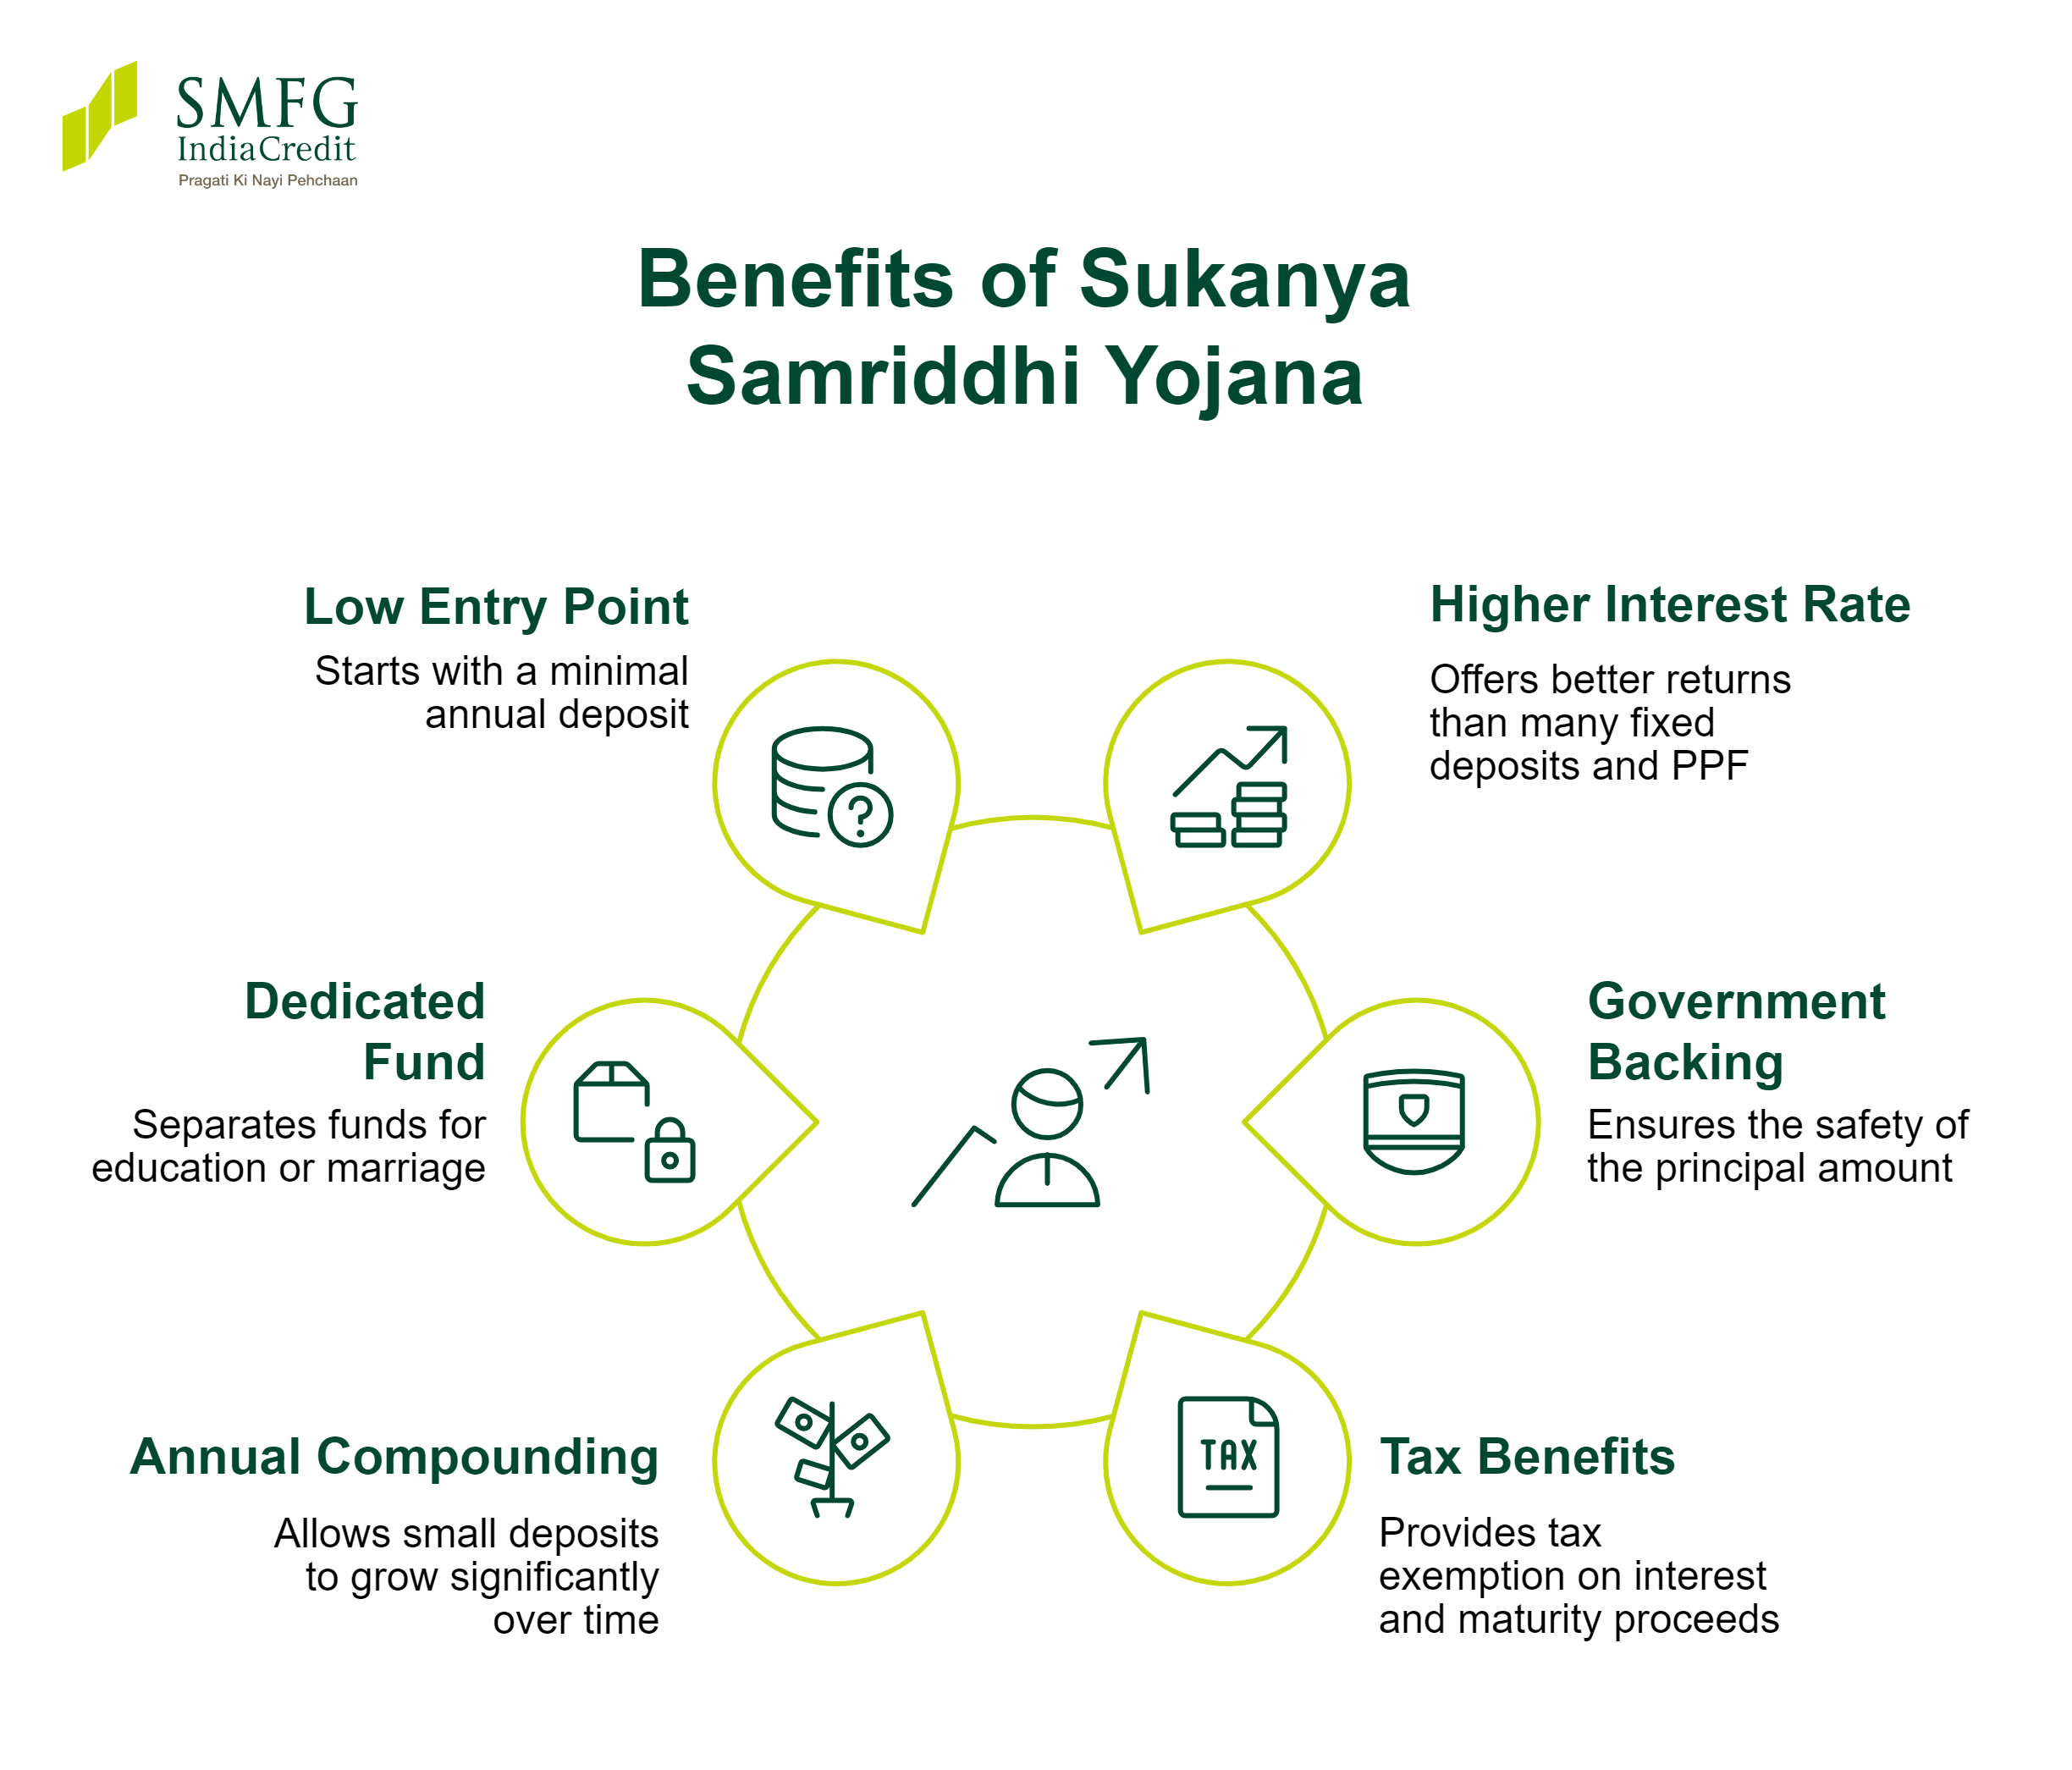
The Sukanya Samriddhi Yojana benefits go well beyond the interest rate. Here's what you actually get:
- A higher rate than many fixed deposits and PPF.
- Full government backing, so your principal is safe.
- A double tax benefit: your interest and maturity proceeds are all tax-free.
- Annual compounding, which lets even small yearly deposits grow into a sizeable amount over 21 years.
- A dedicated fund for your daughter's education or marriage, kept separate from your other savings.
- A low entry point, starting at just Rs. 250 a year.
Together, these benefits of Sukanya Samriddhi Yojana make it one of the more disciplined ways to build a corpus for your daughter without taking on any significant investment risk. This is one reason Sukanya Samriddhi for girl child planning remains popular with Indian parents.
Sukanya Samriddhi Yojana Interest Rate
The Sukanya Samriddhi Yojana offers a government-notified interest rate that is reviewed every quarter. Interest is calculated on the eligible account balance and compounded annually, helping long-term savings grow over the account's tenure.
- Current Interest Rate: 8.2% per annum (July-September FY 2026-27)
- Interest Review: Revised quarterly by the Government of India
- Compounding: Annually
- Interest Credited: At the end of each financial year
Sukanya Samriddhi Yojana Eligibility Criteria
The Sukanya Samriddhi Yojana eligibility rules are straightforward, but worth checking carefully before you visit a bank branch or post office:
- Your daughter must be below 10 years of age when you open the account.
- You, as her parent or legal guardian, open and operate it on her behalf.
- Only one account is allowed per girl child.
- A family can open a maximum of two accounts, with an exception for twins.
- She must be a resident Indian at the time of opening and for as long as the account stays active.
Who Can Open an SSY Account?
A parent or a court-appointed legal guardian can open an SSY scheme account on behalf of an eligible girl child. The account holder must be a resident Indian at the time of opening the account, and the applicable residency conditions under the scheme must continue to be satisfied throughout its tenure.
SSY Age Limit
You can open the account any time from birth until your daughter turns 10. So if she's 9 now, you can still open one; deposits will then run for 15 years from that date, not from her birth.
Sukanya Samriddhi Yojana Deposit Rules
Once your account is open, here's how deposits work:
- Minimum deposit: Rs. 250 a year.
- Maximum deposit: Rs. 1.5 lakh a year.
- You can deposit in one go or in instalments through the year.
- Deposits are required for the first 15 years from account opening.
- After 15 years, you don't need to deposit anything further, but the balance keeps earning interest.
What Happens If You Miss SSY Deposit?
Your SSY account may be treated as a default account if you do not make the minimum annual deposit of Rs. 250. To reactivate a default account, you must pay a penalty of Rs. 50 for each year the minimum deposit was not made, along with the outstanding minimum deposit amount for those years.
If the default account is not reactivated within 15 years from the date of opening, the balance accumulated before the account became inactive will earn only the interest rate applicable to a standard savings account.
How Is Interest Calculated on SSY?
Interest is worked out on the lowest balance in your account between the 5th and the last day of each month, then credited once a year, at the end of the financial year. In practice, this means depositing before the 5th of the month gets that amount counted for interest sooner.
For example, if you deposit Rs. 1.5 lakh every year for 15 years and the interest rate remains 8.2% per annum throughout, the SSY maturity amount could be around Rs. 69-70 lakhs after 21 years. Since the government reviews the interest rate every quarter, the actual maturity value may vary. You can use a Sukanya Samriddhi Yojana calculator to estimate the maturity amount based on different contribution levels and interest rate scenarios.
Sukanya Samriddhi Yojana Maturity Period
Your account matures 21 years after the date you opened it, or earlier if your daughter marries after turning 18. You only need to deposit for the first 15 years; for the remaining 6, your balance sits there and keeps compounding.
Account Timeline: 10, 15, 18 and 21 Years
|
Stage
|
What Happens
|
|
Below 10 years
|
The account can be opened for an eligible girl child.
|
|
15 years from opening
|
The mandatory contribution period ends.
|
|
18 years (account holder's age)
|
Partial withdrawal of up to 50% of the eligible balance is permitted for higher education, subject to the scheme rules. The account may also be closed if the account holder marries after attaining 18 years, subject to the applicable conditions.
|
|
21 years from opening
|
The account matures, and the eligible maturity amount becomes payable.
|
Sukanya Samriddhi Yojana Calculator: How Much Will You Get on Maturity?
An SSY calculator gives you a quick estimate of your daughter's maturity amount based on your yearly deposit, the current interest rate, and the investment period. Since the SSY interest rate may be revised every quarter, it's worth rerunning the SSY maturity calculator whenever the government announces a new rate, rather than relying on a one-time estimate.
SSY Maturity Amount Example
|
Annual Deposit
|
Deposit Period
|
Assumed Interest Rate
|
Approx. Maturity Amount
|
|
Rs. 50,000
|
15 years
|
8.2%
|
~Rs. 23 lakh
|
|
Rs. 1,00,000
|
15 years
|
8.2%
|
~Rs. 46 lakh
|
|
Rs. 1,50,000
|
15 years
|
8.2%
|
~Rs. 69-70 lakh
|
These are indicative figures only. The actual maturity amount will depend on the rate in force each quarter over the full 21-year period.
Sukanya Samriddhi Yojana Tax Benefits
The Sukanya Samriddhi Yojana tax benefit is one of the strongest reasons parents pick this scheme. It carries what's known as EEE status: exempt, exempt, exempt. The Section 80C Sukanya Samriddhi deduction, along with tax-free interest and a tax-free payout, is what makes this SSY tax benefit so valuable over 21 years:
- Your deposits, up to Rs. 1.5 lakh a year, qualify for a deduction under Section 80C.
- The interest you earn is completely tax-free.
- The maturity amount, when your daughter finally withdraws it, is also tax-free.
So, is SSY tax-free? At every stage (deposit, interest, and payout), the answer is yes, provided you stay within the deposit limits and follow the scheme rules. This SSY tax exemption is why many parents treat it as their preferred choice for long-term, low-risk savings.
How to Open a Sukanya Samriddhi Account
Opening an account takes just a few steps:
- Visit an authorised bank branch or a nearby post office offering the scheme.
- Fill in the Sukanya Samriddhi Yojana form with the required details of the girl child, parent or legal guardian.
- Submit the necessary documents, such as the girl's birth certificate and the parent or guardian's identity and address proof.
- Make the initial deposit of at least Rs. 250.
- Once the account is opened, collect the passbook or account confirmation for future transactions.
How to Open Sukanya Samriddhi Account Online
Some authorised banks may allow customers to initiate the account opening process through their internet banking portal or mobile banking application. However, depending on the bank's procedures, you may still need to visit a branch to submit the required documents or complete verification. Since the process differs across banks, it is advisable to check with your chosen bank for the latest account opening requirements.
Sukanya Samriddhi Account Opening: Post Office vs Bank
A Sukanya Samriddhi Yojana account can be opened at any authorised bank or a post office offering the scheme. Both options follow the same government rules regarding eligibility, deposits, interest rates and tax benefits. If you relocate, the account can be transferred between authorised bank branches and post offices anywhere in India, ensuring uninterrupted account management.
|
Parameter
|
Post Office
|
Bank
|
|
Availability
|
Available at designated post offices across India
|
Available at authorised public and private sector banks
|
|
Scheme Rules
|
Government-prescribed rules apply
|
Same government-prescribed rules apply
|
|
Interest Rate
|
Government-notified rate
|
Same government-notified rate
|
|
Deposits & Withdrawals
|
As per scheme guidelines
|
As per scheme guidelines
|
|
Online Services
|
Limited, depending on the post office
|
May offer internet and mobile banking facilities, depending on the bank
|
|
Account Transfer
|
Can be transferred to another post office or an authorised bank
|
Can be transferred to another authorised bank or a post office
|
Documents Required for Sukanya Samriddhi Account
You'll generally need the following Sukanya Samriddhi Yojana documents:
- Birth certificate of the girl child
- Identity proof of the parent or legal guardian, such as Aadhaar, PAN or passport
- Address proof of the parent or legal guardian
- Passport-size photographs, if required by the bank or post office
- A duly completed Sukanya Samriddhi Yojana account opening form
Depending on the authorised bank or post office, additional documents or declarations may be requested to complete the account opening process.
How to Pay Sukanya Samriddhi Yojana Online
Online payments for the SSY scheme depend on the facilities offered by the authorised bank or post office where the account is held. Many banks provide digital payment options, while the availability of online services at post offices may vary. Before making a payment, check the payment methods supported by your account provider.
- Log in to your bank's internet banking portal or mobile banking app, if available.
- Select the Sukanya Samriddhi Yojana account and enter the deposit amount.
- Complete the payment using the available mode, such as net banking, standing instructions, mobile banking or UPI, where supported by the provider.
- If your account is with India Post, use the available India Post digital channels or visit the post office if online payments are not supported.
- Save the transaction confirmation or receipt for your records.
How to Check Sukanya Samriddhi Account Balance
You can check your balance through any of the following methods, depending on the facilities offered by your bank or post office:
- Getting your passbook updated at the branch.
- Visiting your bank branch or post office in person.
- Log in to your bank's internet banking portal or mobile banking app, if this facility is enabled for your account.
- Calling your bank's or post office's customer service.
Sukanya Samriddhi Withdrawal Rules
These rules cover two situations: partial withdrawal while the account is still running, and full withdrawal at maturity.
|
Type
|
When Allowed
|
Limit
|
|
Partial withdrawal
|
After age 18, or after Class 10
|
Up to 50% of the previous year-end balance
|
|
Full withdrawal
|
On maturity (21 years from account opening) or on marriage after attaining 18 years
|
Entire account balance, including accrued interest
|
Partial Withdrawal for Higher Education
A partial withdrawal for higher education generally requires supporting documents such as the account holder's admission letter, fee demand letter, age proof, account passbook and a duly completed withdrawal application form. Depending on the authorised bank or post office, the approved amount may be disbursed as a lump sum or in instalments, so it is advisable to confirm the applicable process with the branch before applying.
Can NRIs Open or Continue Sukanya Samriddhi Account?
No. NRIs cannot open an account under this scheme, and your daughter must remain a resident Indian throughout its term. If her residential status changes after the account is open, you're required to inform your bank or post office, and the account will typically need to be closed.
Since the applicable treatment may change with government notifications, it is advisable to confirm the latest rules with the authorised bank, post office or the official scheme guidelines before taking any action.
SSY vs Mutual Funds for Girl Child Planning
Both Sukanya Samriddhi Yojana and mutual funds can help parents build a corpus for a girl's future, but they differ in terms of returns, risk and liquidity. SSY offers government-backed, fixed returns, whereas mutual fund returns depend on market performance. The suitable option depends on your financial goals, investment horizon and risk tolerance.
|
Parameter
|
SSY
|
Mutual Funds
|
|
Returns
|
Government-notified and revised periodically
|
Market-linked and variable
|
|
Risk
|
Very low
|
Ranges from low to high, depending on the fund type
|
|
Tax Treatment
|
Interest and maturity proceeds are tax-exempt, subject to applicable tax provisions
|
Depends on the type of fund and the applicable tax rules
|
|
Liquidity
|
Limited and governed by scheme rules
|
Generally more flexible, subject to the fund's terms and conditions
|
Disclaimer: This comparison is provided for informational purposes only and does not constitute investment advice. Please assess your financial goals and risk appetite, or consult a qualified financial adviser before making an investment decision.
Who Should Invest in the SSY Scheme?
SSY is suitable for parents and legal guardians who want to build a dedicated corpus for a girl child's future through a government-backed, long-term savings scheme. It may be particularly appropriate for those seeking tax-efficient savings and who are comfortable keeping their money invested until the scheme's withdrawal or maturity conditions are met. However, it may not be suitable for families who require frequent access to their savings or greater flexibility in making withdrawals.
It may be a suitable option if you:
- Want a government-backed savings scheme with relatively low investment risk.
- Are planning for your daughter's higher education or marriage expenses.
- Wish to benefit from the scheme's tax advantages, subject to applicable tax provisions.
- Can make regular contributions over the prescribed deposit period.
- Do not expect to need short-term liquidity or flexible access to the invested amount.
Common Mistakes to Avoid in Sukanya Samriddhi Yojana
A few simple mistakes can reduce the benefits of a Sukanya Samriddhi Yojana account or create unnecessary complications later. Understanding the scheme rules and planning your contributions can help you make the most of this long-term savings option.
- Opening the account late without checking how the 21-year maturity lines up with your daughter's needs.
- Missing the minimum yearly deposit and letting the account go into default.
- Depositing after the 5th of the month when trying to maximise that month's interest.
- Assuming you can deposit more than Rs. 1.5 lakh a year.
- Not reading the withdrawal rules before assuming you can access the funds early.
- Forgetting to get the passbook updated regularly.
- Failing to inform the bank or post office of changes in the account holder's residential status or other important details.
- Mistaking this SSY scheme for an insurance policy or a loan product.
- Expecting the SSY interest rate to stay fixed forever; it's reviewed every quarter.
Tips to Maximise Sukanya Samriddhi Yojana Benefits
A disciplined approach can help you make the most of your Sukanya Samriddhi Yojana account over the long term. Planning your contributions, keeping track of the scheme rules and reviewing your account periodically can help you stay on course towards your financial goals for your daughter's future.
- Open the account as early as possible to maximise the investment period.
- Make regular contributions every year instead of skipping deposits.
- Deposit the amount on or before the 5th of the month, where possible, to optimise monthly interest calculation.
- Plan your annual or lump-sum contributions in advance.
- Stay within the annual deposit limit of Rs. 1.5 lakh.
- Keep your account details and supporting documents updated.
- Monitor the government-notified interest rate after each quarterly review.
- Avoid premature closure unless permitted under the scheme rules.
- Consider complementing SSY with other savings or investment options if your daughter's future education costs are likely to exceed the expected corpus.
Limitations of Sukanya Samriddhi Yojana
While the SSY scheme offers several benefits, it is equally important to understand its limitations before investing. The scheme is designed for long-term savings with specific eligibility and withdrawal conditions, so it may not suit every family's financial needs or investment goals.
- Only available for a girl child under 10.
- Money is locked in for a long period, with limited withdrawal options.
- Annual deposit is capped at Rs. 1.5 lakh.
- The interest rate can change every quarter, so returns aren't fully predictable in advance.
- Not open to NRIs.
- Funds are meant only for education or marriage, not general use.
When Can a Personal Loan Be a Better Option?
Sukanya Samriddhi Yojana is designed to build a long-term corpus for a girl child's higher education and marriage. Since withdrawals are permitted only under specified conditions, it is generally advisable to avoid premature closure for short-term financial needs. If you require funds for an unexpected expense, medical emergency, home renovation, travel, or any other planned purpose unrelated to the scheme's objectives, a personal loan may be a more appropriate option.
Before applying, you can use a personal loan eligibility calculator to estimate the loan amount you may qualify for based on factors such as your income and existing financial obligations. This can help you assess your borrowing options before submitting an application.
When applying, keep your personal loan documents ready to support a smoother verification process. Lenders typically require identity and address proof, income documents, bank statements, and other relevant paperwork depending on your individual profile and their policies at the time of loan application.
Quick Summary: Sukanya Samriddhi Yojana
- A government-backed savings scheme for an eligible girl child below 10 years of age.
- Current SSY interest rate: 8.2% per annum (July-September FY 2026-27).
- Minimum annual deposit of Rs. 250 and maximum annual deposit of Rs. 1.5 lakh.
- Deposits are made for 15 years, while the account matures 21 years from the date of opening.
- Eligible deposits qualify for a deduction under Section 80C, subject to applicable tax provisions.
- Interest earned and maturity proceeds are tax-free, subject to the scheme rules and applicable tax laws.
- Partial withdrawal is permitted for higher education after attaining 18 years of age or passing Class 10, subject to the scheme rules.
- The scheme is available only for eligible resident Indian girl children and cannot be opened by NRIs.
Conclusion
Sukanya Samriddhi Yojana is a government-backed, tax-efficient savings scheme that can help parents build a long-term financial corpus for a girl child's education and marriage. Its combination of government-notified returns and tax benefits makes it a suitable option for disciplined long-term savings. Before investing, however, it is important to understand the annual deposit limits, account maturity period, withdrawal conditions, and liquidity restrictions to ensure the scheme aligns with your financial goals and future funding requirements.
While partial withdrawals are allowed for higher education, keeping the account active until maturity ensures maximum benefits.
If you need additional financial support for your daughter's studies, SMFG India Credit offers personal loans of up to Rs. 10 lakhs* to cover substantial education costs without disrupting your investments. Apply online today for competitive personal loan interest rates starting from 12.5% per annum*.
Review your personal loan eligibility before applying to understand the requirements and prepare your documents accordingly.