The APR full form is Annual Percentage Rate, and it is one of the most important figures you should understand before taking a loan or using a credit card. It represents the total yearly cost of borrowing money. Unlike a standard interest rate, APR includes both interest charges and applicable loan-related fees, giving you a clearer view of the actual cost you will pay.
Many borrowers select a loan based solely on the advertised interest rate. However, this can be misleading because such rates are often nominal and do not factor in processing fees, insurance charges, or administrative costs. As a result, the final borrowing cost may turn out to be higher than expected.
Understanding the APR meaning in finance, and knowing how it is calculated, helps you make more informed borrowing decisions. Whether you are evaluating personal loan interest rates or comparing credit card APRs, this measure ensures fair comparison and protects you from unexpected or hidden charges.
What Is Annual Percentage Rate (APR)?
The Annual Percentage Rate or APR helps you to calculate the actual borrowing cost over a particular period. It is expressed in percentage and represents the yearly cost of the loan.
The Annual Percentage Rate meaning takes into account the nominal interest rate and all other fees involved in getting and servicing the loan. The fees include processing fees, insurance costs, administrative costs, and other miscellaneous expenses. However, it doesn't consider compounding into account while calculating the actual interest cost of the loan.
The Annual Percentage Rate will always be equal to or higher than the nominal interest rate charged on the loan.
APR is a very useful tool in comparing the loan terms of different lenders and helps to find the right lender that suits your needs.
Types of Annual Percentage Rate
There are different types of APR, and understanding them helps you assess borrowing costs more accurately.
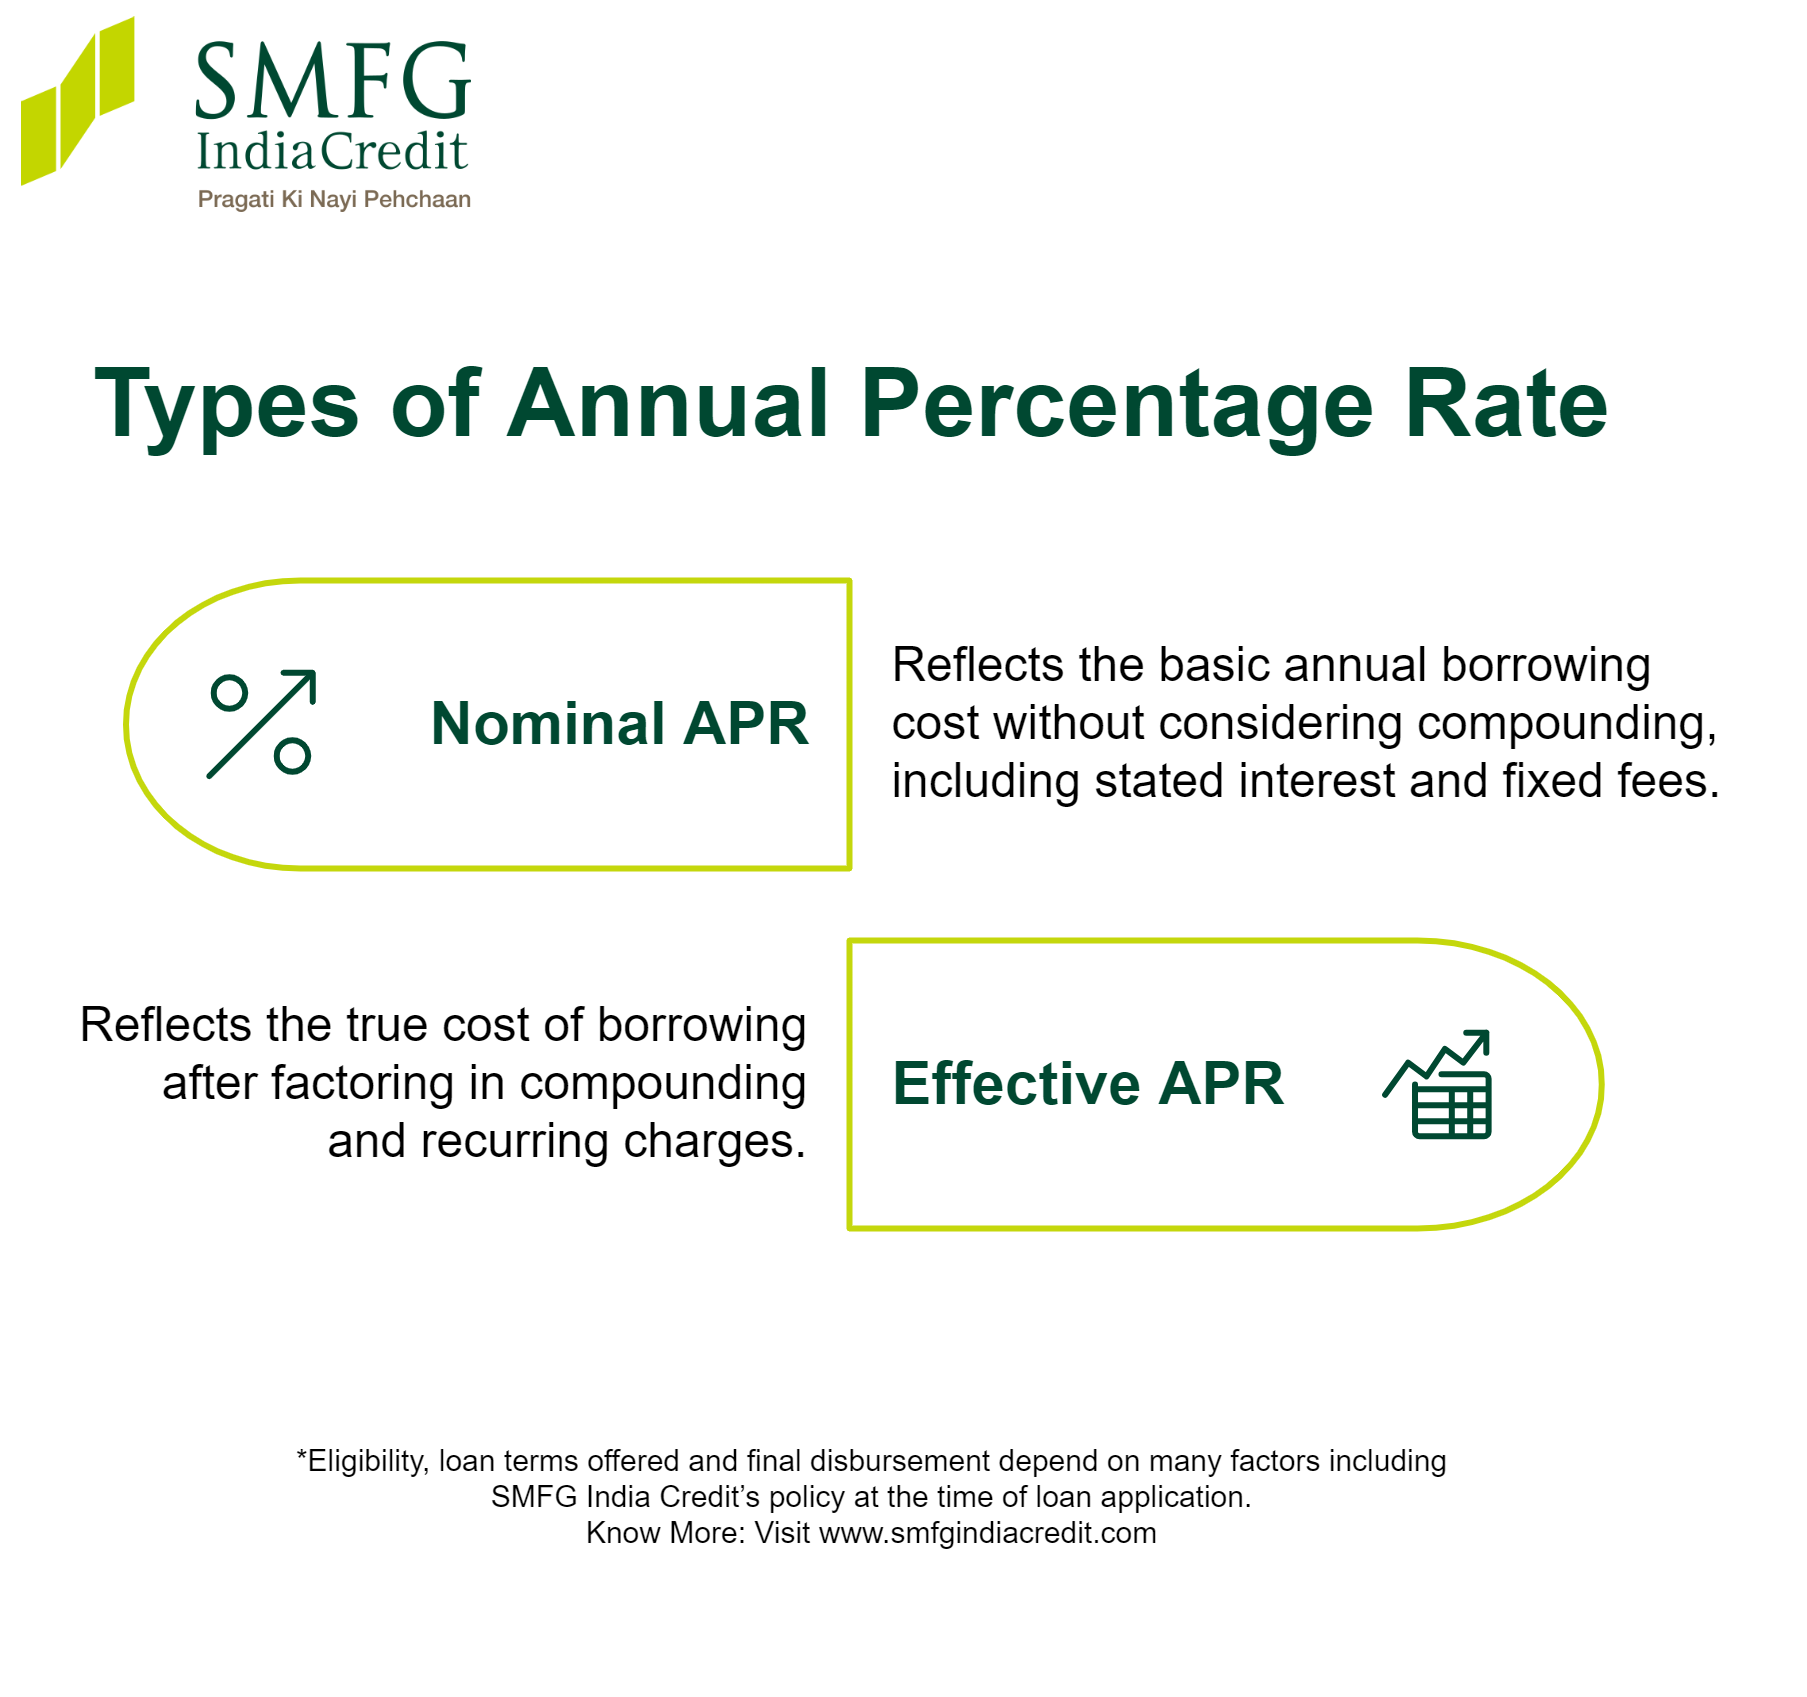
Nominal APR
Nominal APR reflects the basic annual borrowing cost without considering compounding. It usually includes the stated interest rate and certain fixed fees. Nominal APR is commonly used for personal loans with fixed EMIs, where interest is calculated in a straightforward manner.
Effective APR
Effective APR reflects the true cost of borrowing after factoring in compounding and recurring charges. It is particularly relevant for credit card APR, where interest may be calculated daily or monthly.
Understanding nominal APR vs effective APR is important. Nominal APR works well for simple loan products, while effective APR gives a more realistic view for revolving credit, like credit cards.
How APR Works: A Simple Explanation
The Annual Percentage Rate (APR) represents the true yearly cost of borrowing by combining the interest rate with applicable fees and charges. This makes APR a more accurate indicator than the nominal interest rate, which only reflects the interest portion and excludes processing or administrative costs.
Let’s take an APR loan example. Suppose you borrow ₹1,00,000 at a 10% APR. Your total annual borrowing cost would be ₹10,000, which includes both interest and mandatory charges. If the nominal interest rate is 8% and the remaining 2% comes from fees, relying only on the nominal rate would hide the actual borrowing cost. APR highlights this difference in loan fees clearly.
By reviewing APR figures, borrowers can conduct a more precise loan comparison. Even if two lenders offer the same interest rate, their APRs may differ due to variations in fees, helping you choose the more cost-effective option.
To plan better, you can also pair this understanding with tools like a personal loan EMI calculator and personal loan eligibility calculator, which simplify repayment planning and help assess your borrowing capacity.
How Is APR Calculated?
The APR calculation formula is:
APR= [{(Fees + Interest)/ Principal}/ n]*365*100
interest- total interest to be paid during the loan tenure
n- tenure of the loan in days
For example, Vijay wants to apply for a personal loan of Rs 5 lakh with a repayment tenure of 3 years. The interest rate charged on the loan is 12% and, the processing fee is 1.5%, and the insurance cost is Rs 4,700. The APR calculation will be done as follows:
The processing fee is coming at Rs 7,500, and the total fee, including insurance cost, is Rs 12,200. And, the interest cost is Rs 1,80,000.
APR = [{(12,200+1,80,000)/5,00,000}/1095]*365*100 = 12.81%
The actual cost of the loan is coming at 12.81% for the 3-year loan tenure and is higher than the nominal interest rate.
Like every other financial metric, APR too has a few shortcomings, such as it doesn't work with floating interest rates and is not suitable for comparing short-duration loans.
Why Is APR Important?
When it comes to knowing the true cost of borrowing, the annual interest rate (AIR) advertised by lenders fails to reveal the true cost of the loan. And, some lenders, in order to attract customers, deliberately keep the APR lower and keep all other charges high. Thus, hiding the actual total loan fees.
APR is very useful while taking a mortgage loan, such as a loan against property. As the loan tenures go up to 20 years and the list of documents required for a loan against property, verification and appraisal of the loan application is substantial, it often translates into a higher processing fee and administrative costs.
APR vs Annual Percentage Yield (APY)
The comparison between APR vs APY helps borrowers and investors understand how interest is applied. The Annual Percentage Rate definition reflects the yearly cost of borrowing and includes both interest and applicable fees. It is based on simple interest and is typically used for loans, mortgages, and credit cards.
In contrast, Annual Percentage Yield (APY) shows the total interest earned on savings or investments over a year and accounts for compounding. This means interest is calculated on both the principal and previously earned interest.
|
Basis
|
APR
|
APY
|
|
Purpose
|
Cost of borrowing
|
Return on savings
|
|
Includes fees
|
Yes
|
No
|
|
Compounding
|
No
|
Yes
|
APR vs Nominal Interest Rate vs Daily Periodic Rate
Understanding the difference between these terms helps borrowers evaluate credit costs more accurately. Knowing the APR vs nominal interest rate ensures you are not misled by interest-only figures that exclude fees.
The nominal interest rate is the stated rate applied only to the loan principal and does not account for processing fees, insurance charges, or other costs.
APR calculation, on the other hand, includes the nominal interest rate plus applicable fees, represented as an annual percentage. This makes APR far more reliable at the time of loan comparison.
The daily periodic rate is calculated by dividing the nominal interest rate by 365 and is primarily used for daily interest calculations on credit cards.
|
Term
|
What It Represents
|
|
APR
|
Interest plus fees, shown annually
|
|
Nominal interest rate
|
Only the interest component
|
|
Daily periodic rate
|
Daily interest calculation based on the nominal rate
|
How to Lower APR for a Personal Loan
If you want to lower the APR for a personal loan, start by improving your credit score. Lenders generally offer lower APRs to borrowers with a strong repayment history and low credit risk. Comparing APRs and loan offers across multiple lenders can also help you identify more competitive rates.
Opting for a shorter loan tenure may reduce the overall borrowing cost and improve your chances of securing a lower APR. Additionally, try negotiating processing fees and other charges since APR accounts for these costs in its calculation.
Steps on how to reduce APR on loans:
- Improve your credit score
- Compare APRs across lenders
- Opt for shorter tenures
- Negotiate interest rates and other applicable fees where possible
What Is a Good APR?
A good APR depends on the type of loan you choose and your overall financial profile. For personal loans, borrowers with strong credit scores and stable income typically qualify for lower APRs. Credit card APRs are generally higher because they involve revolving credit, whereas mortgage APRs tend to be lower due to longer repayment periods and the presence of collateral.
Your credit score, loan amount, tenure, and repayment capacity all influence what is considered a favourable APR. Always compare APRs from multiple lenders to find a rate that balances affordability with comfortable repayment.
Conclusion
Using the Annual Percentage Rate (APR) not only gives you a better idea of the cost of a loan beforehand, but also helps you to choose the lender wisely and get the best loan deals.
Therefore, whenever you apply for a loan, make sure you confirm the APR with your lender before signing the loan documents.
If you’re exploring financing options, SMFG India Credit offers personal loans of up to Rs. 10 lakhs* with interest rates starting from only 12.5%* per annum. Check your personal loan eligibility and apply online using minimal personal loan documents.