The final EMI is not always the last part of the bike loan closure process. After your loan is fully repaid, you should collect the NOC for bike loan from your lender and complete the formalities to remove hypothecation from your Registration Certificate (RC). The NOC confirms that your loan account has no pending dues and that the lender no longer has a financial claim over the financed vehicle.
This guide explains what an NOC for a bike is, how to obtain one online or offline, what to do after receiving it, and how to update your vehicle records.
What Is NOC for a Bike Loan?
A No Objection Certificate (NOC) is a document issued by your lender after you complete the full loan repayment and clear any applicable dues.
The bike loan NOC meaning essentially refers to the lender's confirmation that there are no outstanding dues against the closed loan and that the lender has no further financial claim over the vehicle.
The No Objection Certificate for a bike loan acts as proof of loan closure and is often referred to as a no-dues document or a bike loan closure certificate. Once your two-wheeler loan is closed, the NOC can be used as part of the process to remove the lender's hypothecation from the RC. Completing this step ensures the vehicle registration records no longer reflect the lender's interest, leaving your bike ownership records updated accordingly.
Why Is a Two-Wheeler Loan NOC Important?
Paying off your bike loan clears the debt, but the lender's name may still appear on the RC until the required formalities are completed. The importance of a two-wheeler loan NOC lies in documenting that the lender has cleared the loan from its end and enabling you to update the records associated with the vehicle. This is why a bike loan NOC is needed even after the last EMI has been paid.
- Records the Loan Closure: The bike loan no dues certificate provides loan closure proof and confirms that there are no pending dues.
- Allows Hypothecation Removal: The document supports the process of removing hypothecation from the vehicle registration records after repayment.
- Makes Future Transfers Easier: Clearing the financier's details from the records can prevent complications during an ownership transfer.
- Helps When Selling the Bike: An updated RC can make a future vehicle sale easier by showing that the financier's interest has been removed.
- Creates a Clear Record: Retaining the NOC helps establish that the lender's claim over the financed vehicle has ended.
If the NOC is not obtained and the registration records are not updated, the lender's details may continue to appear against the bike despite the loan having been fully repaid.
When Do You Need a Bike Loan NOC?
An NOC after bike loan closure becomes relevant once the loan is fully repaid and may also be needed for certain changes to the vehicle records. Common situations include:
- After paying the final EMI and completing the loan closure formalities.
- When applying for hypothecation removal from the vehicle's RC.
- When selling the bike and completing an ownership transfer with an NOC for bike transfer.
- When completing a state transfer that requires changes to the vehicle registration.
- When approaching the RTO for certain registration-related formalities.
- When applying for a duplicate RC, where supporting documents may be required depending on the circumstances.
The exact documents and steps can vary depending on the Regional Transport Office (RTO), the lender, and the services available through VAHAN or Parivahan Sewa.
How to Get NOC for Bike Loan After Loan Closure
Once the repayment is complete, the bike loan NOC process involves confirming that the lender has closed the finance agreement and has no further dues to recover. Here is how to get a bike loan NOC after repayment:
- Clear all EMIs and any remaining outstanding dues on the loan account.
- Confirm the loan closure with your lender.
- Request the NOC letter through the lender's available online or offline channel.
- Check the bike loan NOC carefully to ensure the borrower, vehicle, and loan details are correct.
- Collect or download the NOC and Form 35, where provided or applicable.
The exact steps to get a two-wheeler loan NOC may vary by the lender or the Non-Banking Financial Company (NBFC), so check the process applicable to your loan.
Step-by-Step Process to Get Two-Wheeler Loan NOC
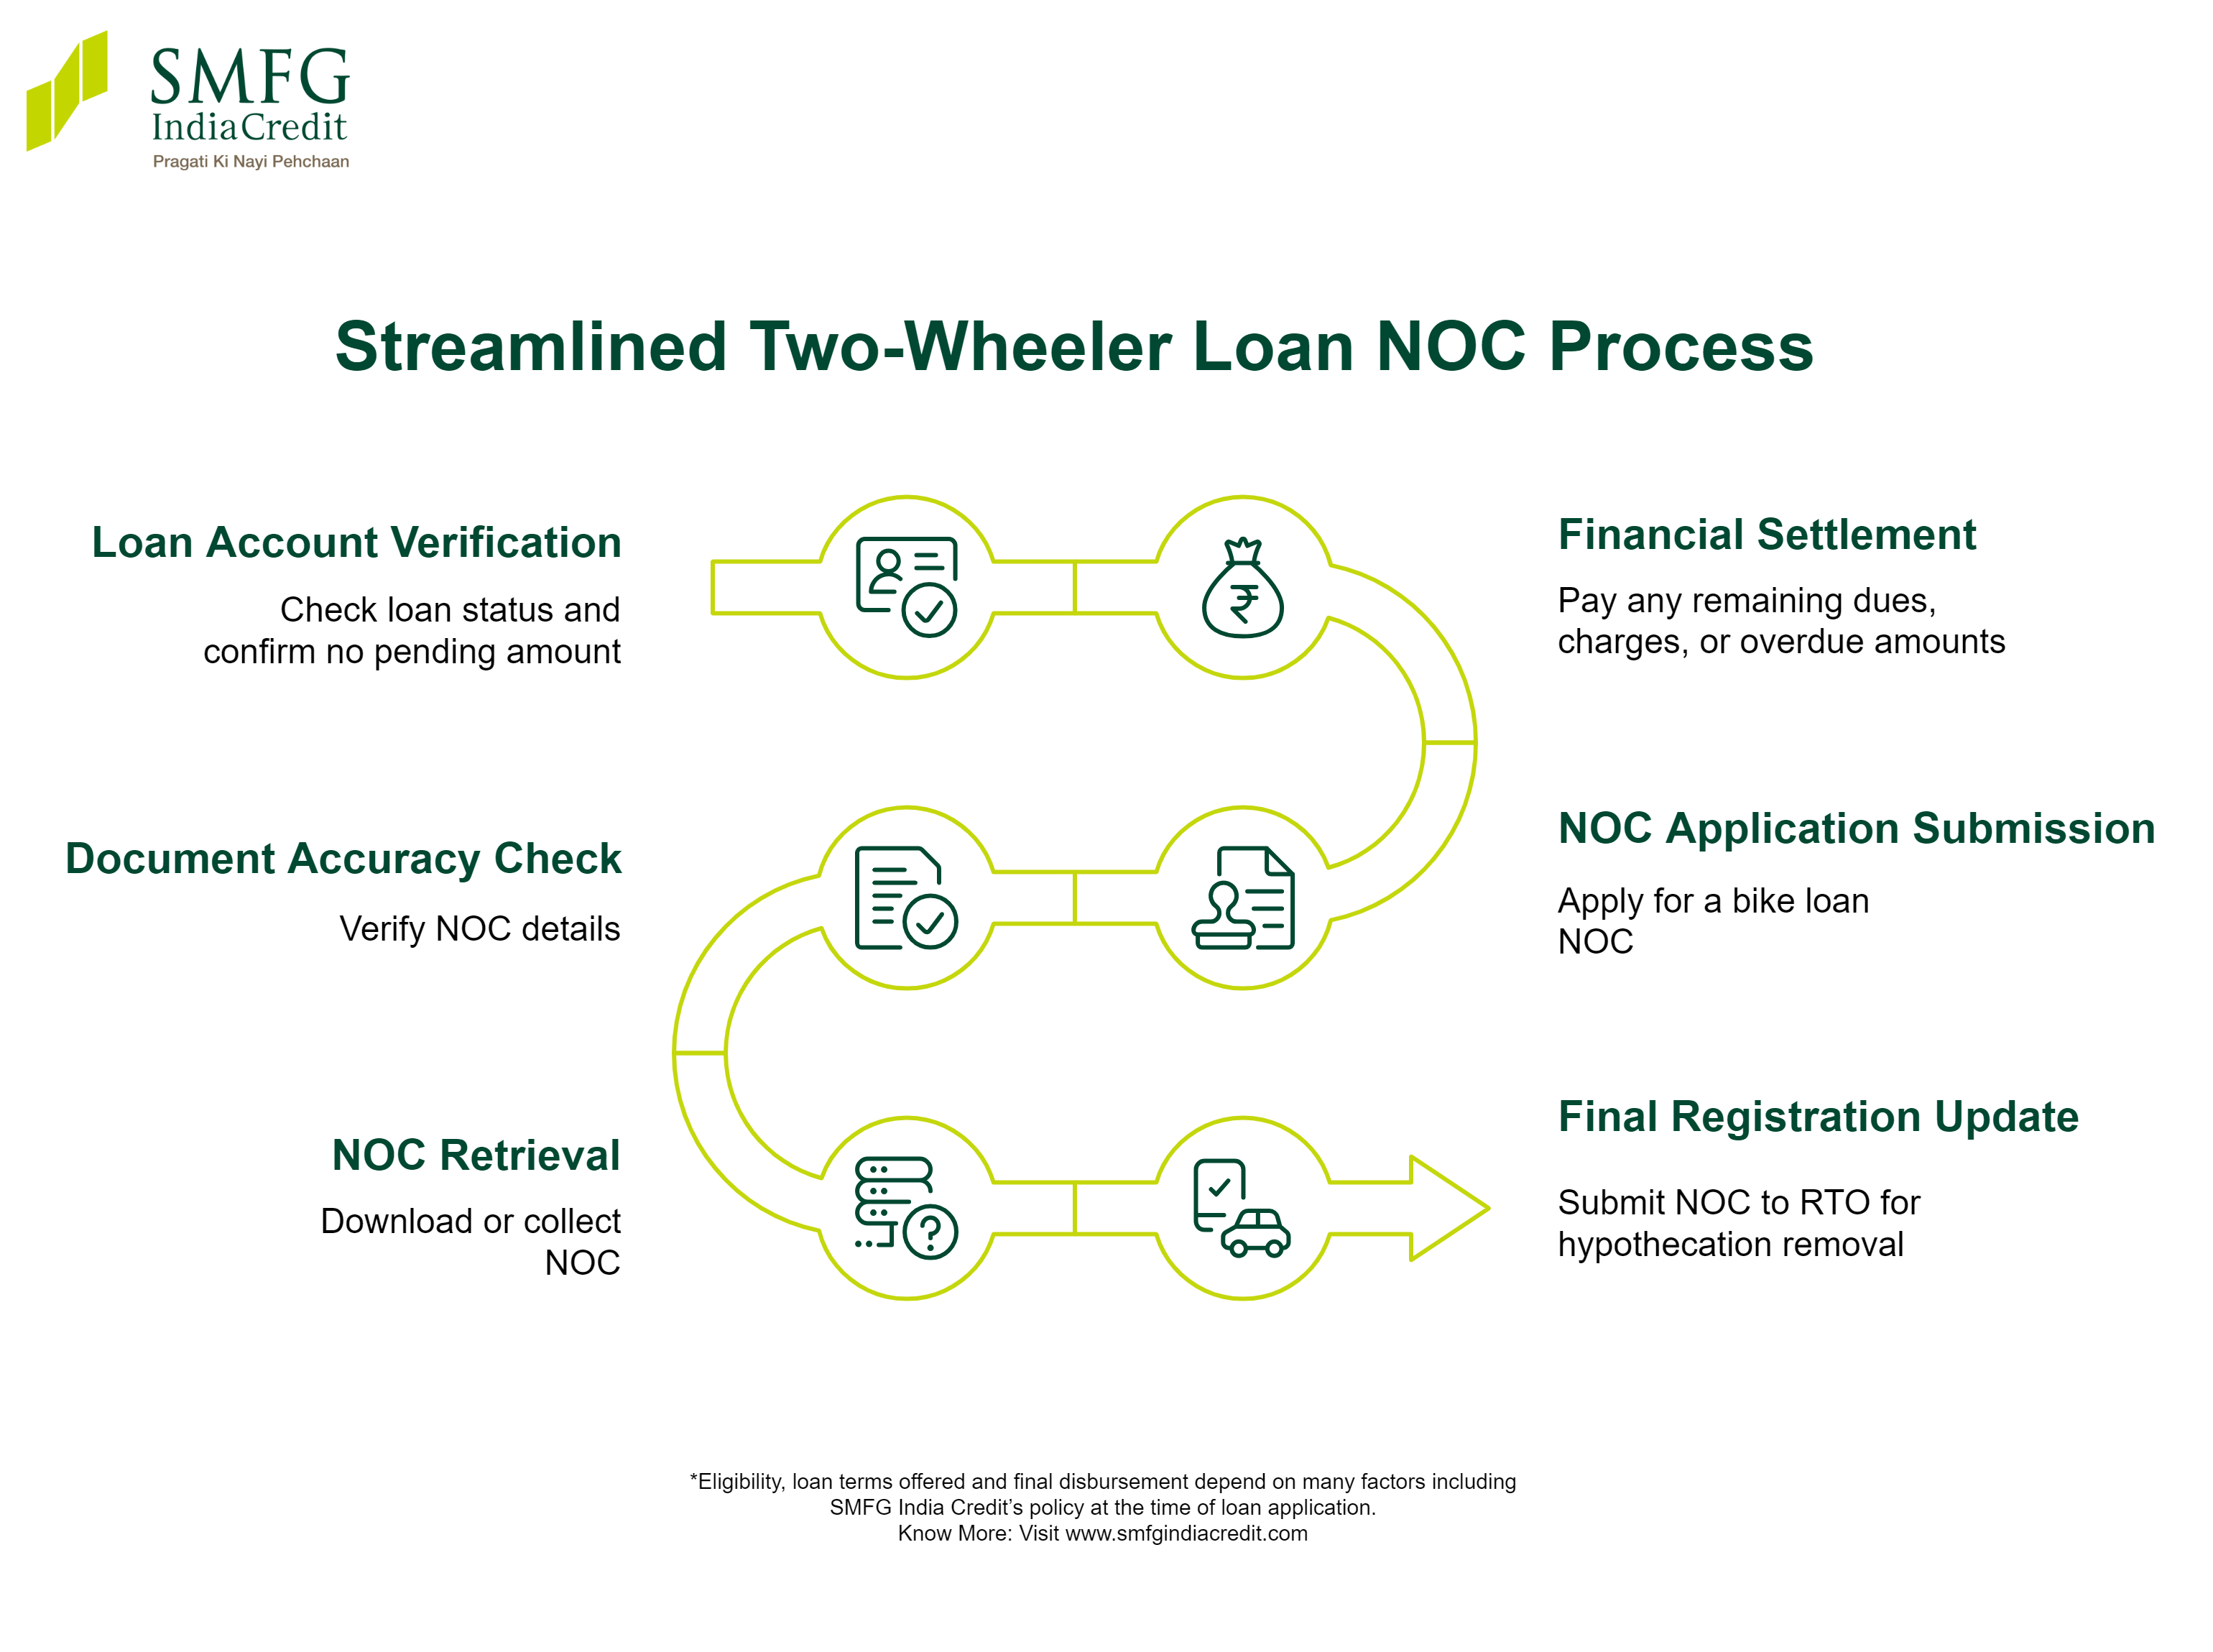
The two-wheeler loan NOC process is fairly straightforward once your repayment is complete. These bike loan NOC steps can help you move from loan closure to updating the vehicle records:
- Check the status of your loan and confirm that the loan account number shows no pending amount.
- Pay any remaining dues, charges, or overdue amounts, if applicable.
- Apply for a bike loan NOC through the lender's branch, customer service channel, or lender portal, where available.
- Verify that the NOC correctly mentions the vehicle registration number, chassis number, engine number, and loan details.
- Download the bike loan NOC or collect the physical copy, depending on the lender's process.
- Submit the NOC and other required documents to the RTO to complete hypothecation removal from the RC.
How to Download Bike Loan NOC Online
If your lender provides a digital facility, you may be able to download bike loan NOC online without visiting a branch. The exact bike loan NOC download process varies by lender, but it generally involves the following:
- Sign in to the lender website, lender app, or customer portal using your registered mobile number or other credentials.
- Select the relevant loan account and confirm that its status shows as closed.
- Look for the option to access your two-wheeler loan NOC online or request a duplicate, if needed.
- Download the digital NOC as a PDF and save or print a copy for your records and further formalities.
How to Get Bike Loan NOC Offline
You can get a bike loan NOC offline if an online download option is unavailable or you prefer to complete the request in person. The process for obtaining a 2-wheeler NOC offline can differ by lender.
- Visit the nearest lender branch that handles your loan or related service requests.
- Carry your identity proof and relevant loan account details to help the lender locate your records.
- Submit an application request for the NOC and provide any additional information or documents required.
- The lender will verify that the loan has been fully repaid and the account is closed.
- Once verified, the NOC letter may be handed over at the branch, posted to your address, or sent by email, depending on the lender's policy.
Keep a copy of the bike loan NOC from a branch safely for the subsequent RC and hypothecation-removal formalities.
Documents Required to Get Bike Loan NOC
The documents required for a bike loan NOC help the lender identify the closed loan and match it with the financed vehicle. Keep the following 2-wheeler NOC documents or details available when raising your request.
|
Document/Detail
|
Why It Is Needed
|
Example
|
|
Loan Account Number
|
To locate the closed loan in the lender's records
|
Loan agreement or statement
|
|
Vehicle Registration Number/RC Number
|
To identify the financed two-wheeler
|
MH01XX1234
|
|
Identity Proof
|
To verify the borrower's identity
|
PAN card or Aadhaar card
|
|
Repayment Record
|
To support confirmation of completed repayment, if requested
|
Repayment receipt
|
|
Loan Closure Record
|
To confirm that the account has been closed
|
Loan closure statement
|
This bike loan NOC document list is indicative. Exact requirements may vary by lender.
What Details Should Be Mentioned in a Bike Loan NOC?
Before using the NOC for further vehicle-related formalities, check that the information on it matches your loan and bike records. A typical bike loan NOC format should contain the following NOC details:
- Borrower Name: The name of the person who took the two-wheeler loan.
- Lender Name: The financial institution that financed the vehicle.
- Loan Account Number: The reference used to identify the closed loan.
- Vehicle Number: The bike's registered number as recorded on the RC.
- Chassis Number and Engine Number: Vehicle identifiers that help link the NOC to the correct bike.
- Loan Closure Confirmation: A statement confirming that the loan has been fully repaid with no outstanding dues.
- Issue Details: The date of issue and the authorised signatory's signature or official seal, as applicable.
Review the two-wheeler loan NOC letter carefully and contact the lender if any information is incorrect or missing.
Bike Loan NOC Format: Key Fields
Use the following NOC letter format for a bike loan as a reference when checking whether the important vehicle and lender details have been recorded correctly.
|
Field
|
Why to Check
|
|
Borrower Name
|
Confirms that the NOC has been issued for the correct loan holder
|
|
Loan Account Number
|
Links the document to the relevant closed loan account
|
|
Registration Number
|
Confirms that the NOC refers to the correct registered vehicle
|
|
Chassis Number
|
Helps verify the specific vehicle against its identification records
|
|
Engine Number
|
Provides another identifier for matching the NOC with the financed bike
|
|
Loan Closure/No-Dues Confirmation
|
Confirms that the loan has been repaid and no dues remain
|
|
NOC Date
|
Shows when the lender issued the document
|
|
Authorised Signature/Lender Seal
|
Helps establish that the NOC was formally issued by the lender
|
What to Do After Receiving a Bike Loan NOC
Once you receive the NOC for a two-wheeler, check all borrower, loan, and vehicle details before proceeding with the remaining closure formalities. You should then:
- Keep the original NOC and a digital copy safely for future reference.
- Collect Form 35 from the lender, where applicable.
- Apply for removal of hypothecation from the RC through the relevant RTO process.
- Check the updated RC to ensure the lender's details have been removed.
- Retain the loan closure certificate for a bike loan with your vehicle records.
How to Remove Hypothecation from RC After Loan Closure
Under the Motor Vehicles Act, 1988 and the applicable Central Motor Vehicles Rules, you need to apply for termination of the hypothecation agreement.
- Obtain the lender's NOC or due-clearance certificate and duly completed Form 35.
- Apply for hypothecation termination through the relevant RTO or the vehicle-related services available on VAHAN through Parivahan Sewa.
- Submit the RC and other applicable documents, which may include a valid motor insurance policy certificate, address proof, PUC certificate, and lender NOC.
- Pay the prescribed fee and complete any verification required by the registering authority.
- Once approved, check the updated RC to confirm that the financier's hypothecation entry has been removed.
The exact process and document requirements can vary by state and registering authority.
Bike Loan NOC vs RTO NOC: Difference
A bike loan NOC and an RTO-issued NOC serve different purposes. Understanding two-wheeler loan NOC vs vehicle NOC is important because one deals with loan closure, while the other relates to moving a vehicle between registration jurisdictions.
|
Point of Difference
|
Bike Loan NOC
|
RTO NOC
|
|
Issued By
|
Lender or financing institution
|
Relevant registration authority
|
|
Purpose
|
A lender NOC confirms that the financed loan has been cleared and the lender has no remaining financial claim over the vehicle
|
An RTO NOC confirms that there is no objection to transferring the vehicle to another registering authority
|
|
When Required
|
Commonly used for removing hypothecation after loan closure
|
Generally required for a state transfer or re-registration under another RTO
|
|
Role in Transfer
|
May be relevant if finance-related records need to be cleared before a transaction
|
An RTO NOC for a bike may be required when an ownership transfer also involves movement to another registering authority
|
The document you need therefore depends on whether you are closing the vehicle loan or transferring its registration to another jurisdiction.
The Role of the NOC in the RTO Process
The NOC issued by your lender is an important part of updating the vehicle records after the loan has been closed. For hypothecation termination, the applicable process generally requires you to:
- Submit the NOC and Form 35, where applicable.
- Provide the RC and supporting documents.
- Pay the applicable fee for the service.
- Complete an online request through VAHAN or Parivahan Sewa, where available.
- Check the updated RC after processing to confirm that the financier’s hypothecation details have been removed.
The exact documents and procedure may differ depending on the state and registering authority.
Tips for a Smooth NOC Process
Before requesting the NOC, make sure your loan and contact details are in order. Once you receive it, check the document carefully and keep the records you may need for the RC update:
- Confirm that all EMIs and any other applicable dues have been cleared.
- Save the final repayment receipt as proof of completed payment.
- Make sure your registered mobile number and address are updated with the lender.
- Check the NOC for errors in your name, loan details, and vehicle information.
- Start the RC update and hypothecation-removal process soon after receiving the NOC.
- Keep copies of Form 35, the NOC, repayment receipts, and other loan closure documents for future reference.
Common Mistakes to Avoid After Getting Bike Loan NOC
Receiving the NOC does not complete every loan closure formality. Some bike loan NOC mistakes can leave the lender's interest recorded against the vehicle or create problems when you need to update or transfer the bike later.
- Failing to verify the NOC details, including your name, loan account, and vehicle information.
- Assuming hypothecation will disappear from the vehicle records automatically once the loan is repaid.
- Delaying submission of the required documents to the RTO, particularly where the NOC has a specified validity period.
- Misplacing Form 35 or other documents needed to terminate the hypothecation agreement.
- Completing the application but failing to check whether the RC update has actually been processed.
- Losing the original NOC before the required formalities are completed.
Avoiding these hypothecation removal mistakes and other two-wheeler loan closure mistakes helps ensure your registration records accurately reflect the closed loan.
What If You Lose Your Bike Loan NOC?
If you lose the original document, contact the lender and ask about a duplicate bike loan NOC. Some lenders allow you to request or download a duplicate copy through their online portal, while others may require a branch visit or service request.
Keep your loan account details and identity documents ready to help the lender verify your request.
Can a Bike Loan NOC Be Reissued or Cancelled?
A lender may reissue a 2-wheeler NOC after verifying your loan and vehicle details. If you need to cancel an RTO-issued NOC or change a vehicle transfer request, the process can depend on the issuing authority and the reason for cancellation.
Contact the relevant Lender or RTO before making changes. Do not assume that a document can be cancelled or reissued without a formal process.
Conclusion
Completing bike loan closure properly involves taking care of the vehicle records after the final repayment. The NOC for a bike loan confirms that no dues remain with the lender, and the two-wheeler loan NOC further supports the next steps for hypothecation removal from the RC. Collect the NOC or Form 35 promptly, check that the loan and vehicle details are accurate, and submit the required documents to the RTO. Once processed, verify that your updated RC no longer carries the lender's hypothecation details.
If you're planning ahead for your bike purchase, SMFG India Credit offers vehicle financing with flexible repayment tenures and competitive two-wheeler loan interest rates.
Check your two-wheeler loan eligibility to understand whether you meet the applicable requirements before applying online.
Before proceeding with the application, use our two-wheeler loan EMI calculator to estimate your monthly repayments across different loan amounts and tenures and plan your finances accordingly.