Introduction: What Is Debt Service Coverage Ratio?
The Debt Service Coverage Ratio measures whether a business generates enough operating income to meet its debt repayment obligations. Expressed as a DSCR ratio, it compares the cash available for servicing debt with the total principal and interest due over a given period. Understanding the DSCR formula helps business owners assess repayment capacity.
This article explains the Debt Service Coverage Ratio formula, how to interpret the ratio, and why it matters when evaluating a business's financial health.
What Is the Debt Service Coverage Ratio?
The DSCR is a financial ratio that evaluates a company's ability to pay its debt obligations from its operating cash flow. Debt service refers to cash required to cover the principal and interest payments on a loan during a given period. Lenders and investors often look at DSCR to gauge whether a business generates sufficient income to cover its debt repayments.
DSCR Full Form and Meaning
The DSCR full form is Debt Service Coverage Ratio.
In lending and finance, the Debt Service Coverage Ratio meaning refers to a business's ability to generate sufficient operating income to meet its debt obligations. The DSCR compares available operating cash flow with annual loan repayments, making it an important indicator of financial stability.
Debt Service Coverage Ratio Formula
The standard DSCR formula is:
DSCR = Net Operating Income (NOI) ÷ Total Debt Service
Here, NOI represents the income generated from business operations after operating expenses, while Total Debt Service includes the scheduled principal and interest repayments for the assessment period. Depending on the lender's credit policy or the type of loan, the DSCR calculation may also use EBITDA or net cash accruals instead of NOI to assess repayment capacity.
Components of DSCR Formula
The DSCR ratio formula has two key components that determine a business's ability to repay its debt.
|
Component
|
Meaning
|
Includes
|
Generally Excludes
|
|
Net Operating Income (NOI)
|
Income generated from core business operations
|
Operating income after operating expenses such as rent, salaries, utilities, and other day-to-day business costs
|
Taxes, interest, one-time income, personal expenses and certain non-cash adjustments (depending on the calculation method)
|
|
Total Debt Service
|
Total annual loan repayment obligation
|
Principal repayment, interest payment, lease obligations (where applicable)
|
Future borrowings and unrelated business expenses
|
Since calculations may use slightly different methods, businesses should confirm whether the assessment is based on net operating income DSCR, EBITDA, or net cash accruals before applying for financing products, such as a business loan.
How to Calculate Debt Service Coverage Ratio
The process is straightforward and requires a few key financial figures from your annual financial statements.
- Calculate Annual Revenue: Determine the total income generated from your business operations during the year.
- Subtract Operating Expenses: Deduct regular business expenses such as salaries, rent, utilities and raw material costs to arrive at NOI. Depending on the assessment method, items such as interest, taxes, or depreciation may be treated differently.
- Calculate Total Debt Service: Add together all annual principal repayment and interest payment obligations for existing loans. This forms the total debt service calculation.
- Apply the Formula: Divide NOI by Total Debt Service using the DSCR ratio formula:
DSCR = Net Operating Income ÷ Total Debt Service
- Interpret the Result: A higher DSCR ratio generally indicates stronger repayment capacity, while a lower value may suggest tighter cash flow.
When learning how to calculate the DSCR ratio, remember that using consistent annual figures is essential for an accurate assessment.
DSCR Calculation Example
The following DSCR calculation example shows how the ratio is calculated using annual financial figures.
|
Particulars
|
Amount
|
|
Annual Revenue
|
Rs. 25,00,000
|
|
Operating Expenses
|
Rs. 15,00,000
|
|
Net Operating Income (NOI)
|
Rs. 10,00,000
|
|
Annual Total Debt Service
|
Rs. 4,00,000
|
|
DSCR
|
2.5
|
A DSCR of 2.5 means the business generates 2.5 times the income required to meet its annual debt obligations. This is a positive indicator for lenders when assessing business loan eligibility and repayment capacity.
Tip: After estimating your DSCR, you can use a business loan EMI calculator to understand how different loan amounts, interest rates, and repayment tenures may affect your monthly repayments. This can help you choose a repayment plan that aligns with your business's cash flow.
DSCR Calculation Table with Multiple Scenarios.
Different DSCR values indicate varying levels of repayment capacity. The table below illustrates how lenders and other stakeholders may interpret different DSCR scenarios.
|
Annual NOI
|
Annual Debt Service
|
DSCR
|
Interpretation
|
|
Rs. 10,00,000
|
Rs. 8,00,000
|
1.25
|
Adequate repayment capacity with a reasonable margin of safety
|
|
Rs. 10,00,000
|
Rs. 10,00,000
|
1.00
|
Income is just sufficient to meet annual debt obligations
|
|
Rs. 10,00,000
|
Rs. 12,00,000
|
0.83
|
Income is below debt obligations, indicating that cash flow may be insufficient for repayments
|
|
Rs. 15,00,000
|
Rs. 6,00,000
|
2.50
|
Strong repayment capacity with a comfortable margin to service debt
|
*The minimum acceptable DSCR may vary depending on the industry, business profile, and loan type. These examples are illustrative and should not be interpreted as universal benchmarks.
How to Interpret DSCR Ratio
The DSCR ratio interpretation helps businesses understand how comfortably operating income can cover annual debt obligations.
|
DSCR Value
|
Interpretation
|
What It May Indicate
|
|
Below 1.0
|
Income is lower than annual debt obligations
|
Higher repayment risk and possible cash flow shortage
|
|
1.0
|
Income exactly covers debt obligations
|
Limited financial cushion for unexpected expenses
|
|
Above 1.0
|
Income exceeds annual repayments
|
Better ability to service debt
|
|
1.25 or higher
|
Generally considered a good DSCR ratio
|
Often preferred by lenders for business financing
|
DSCR Less Than 1
A DSCR below 1 meaning is that the business does not generate enough operating income to fully cover its annual debt repayments. This may affect loan approval or require additional collateral, improved cash flow or revised borrowing terms before financing is approved.
DSCR Equal to 1
A DSCR of 1 means the business earns just enough to meet its annual debt obligations. While repayments may still be possible, there is little margin to absorb a decline in revenue or an increase in expenses.
DSCR Above 1.25
Many lenders consider a DSCR of around 1.25 or higher to be a comfortable level because it provides a buffer above annual repayment obligations. However, the acceptable ratio varies depending on the industry, loan amount, business performance and the lender's credit assessment process.
Tip: A healthy DSCR is only one part of the assessment. Maintaining complete and accurate business loan documents, including CA-audited financial statements and tax records, can help support your repayment capacity verification during the lender's evaluation.
What Is a Good DSCR Ratio?
A good DSCR ratio is generally considered to be above 1, meaning the business can cover its debt service from its operating income. However, the minimum DSCR for business loans is often 1.25 to account for any unexpected fluctuations in income or expenses.
Why DSCR Is Important for Business Loans
A healthy DSCR can help:
- Demonstrate that the business generates sufficient income to meet its debt repayment obligations.
- Strengthen a lender's assessment of the business's repayment capacity.
- Support decisions on an appropriate loan amount and repayment tenure.
- Influence financing terms, including business loan interest rates, depending on the lender's overall credit assessment.
- Encourage better cash flow management and long-term financial planning.
- Evaluate whether taking on additional debt is financially sustainable.
Average DSCR and Projected DSCR
Besides the current DSCR, lenders may also review the average DSCR and projected DSCR during a loan assessment. The average DSCR is typically calculated using historical or projected financial data over multiple reporting periods to evaluate the consistency of a business's repayment capacity. A projected DSCR estimates future repayment ability based on expected income, expenses, cash flows, and debt obligations. Since these projections rely on assumptions, businesses should use realistic financial estimates supported by reliable financial forecasts.
DSCR for MSMEs and Small Businesses
For MSMEs and small businesses, DSCR is an important financial indicator before taking on new borrowing.
Whether applying for a startup business loan or another form of business financing, enterprises should:
- Calculate their current DSCR using recent financial statements.
- Review expected cash flow after taking on new debt.
- Consider seasonal fluctuations in revenue.
- Avoid borrowing beyond their repayment capacity.
- Monitor the ratio regularly as the business grows.
A healthy DSCR ratio supports informed borrowing decisions and helps businesses maintain long-term financial stability.
Factors Affecting Debt Service Coverage Ratio
Several business and financial factors can influence the Debt Service Coverage Ratio.
Key factors include:
- Growth or decline in revenue
- Changes in operating expenses
- Existing debt levels and repayment obligations
- Interest rate increases that raise borrowing costs
- Principal repayment schedules
- Seasonal fluctuations in sales
- Delayed customer payments affecting cash flow
- Business profit margins
- Working capital management
- Loan tenure and repayment structure
- One-time or non-recurring income that may not reflect normal business performance
How Interest Rate and Tenure Impact DSCR
Interest rates and loan tenure directly affect a company's DSCR. When interest rates rise, annual interest payments increase, raising total debt service and potentially reducing the ratio if operating income remains unchanged. Conversely, extending the loan tenure may lower annual repayment obligations, which can improve the DSCR ratio. However, a longer tenure may also increase the total interest paid over the life of the loan. Businesses should evaluate both repayment affordability and overall borrowing costs before choosing a loan structure.
What Are the Advantages & Disadvantages of DSCR?
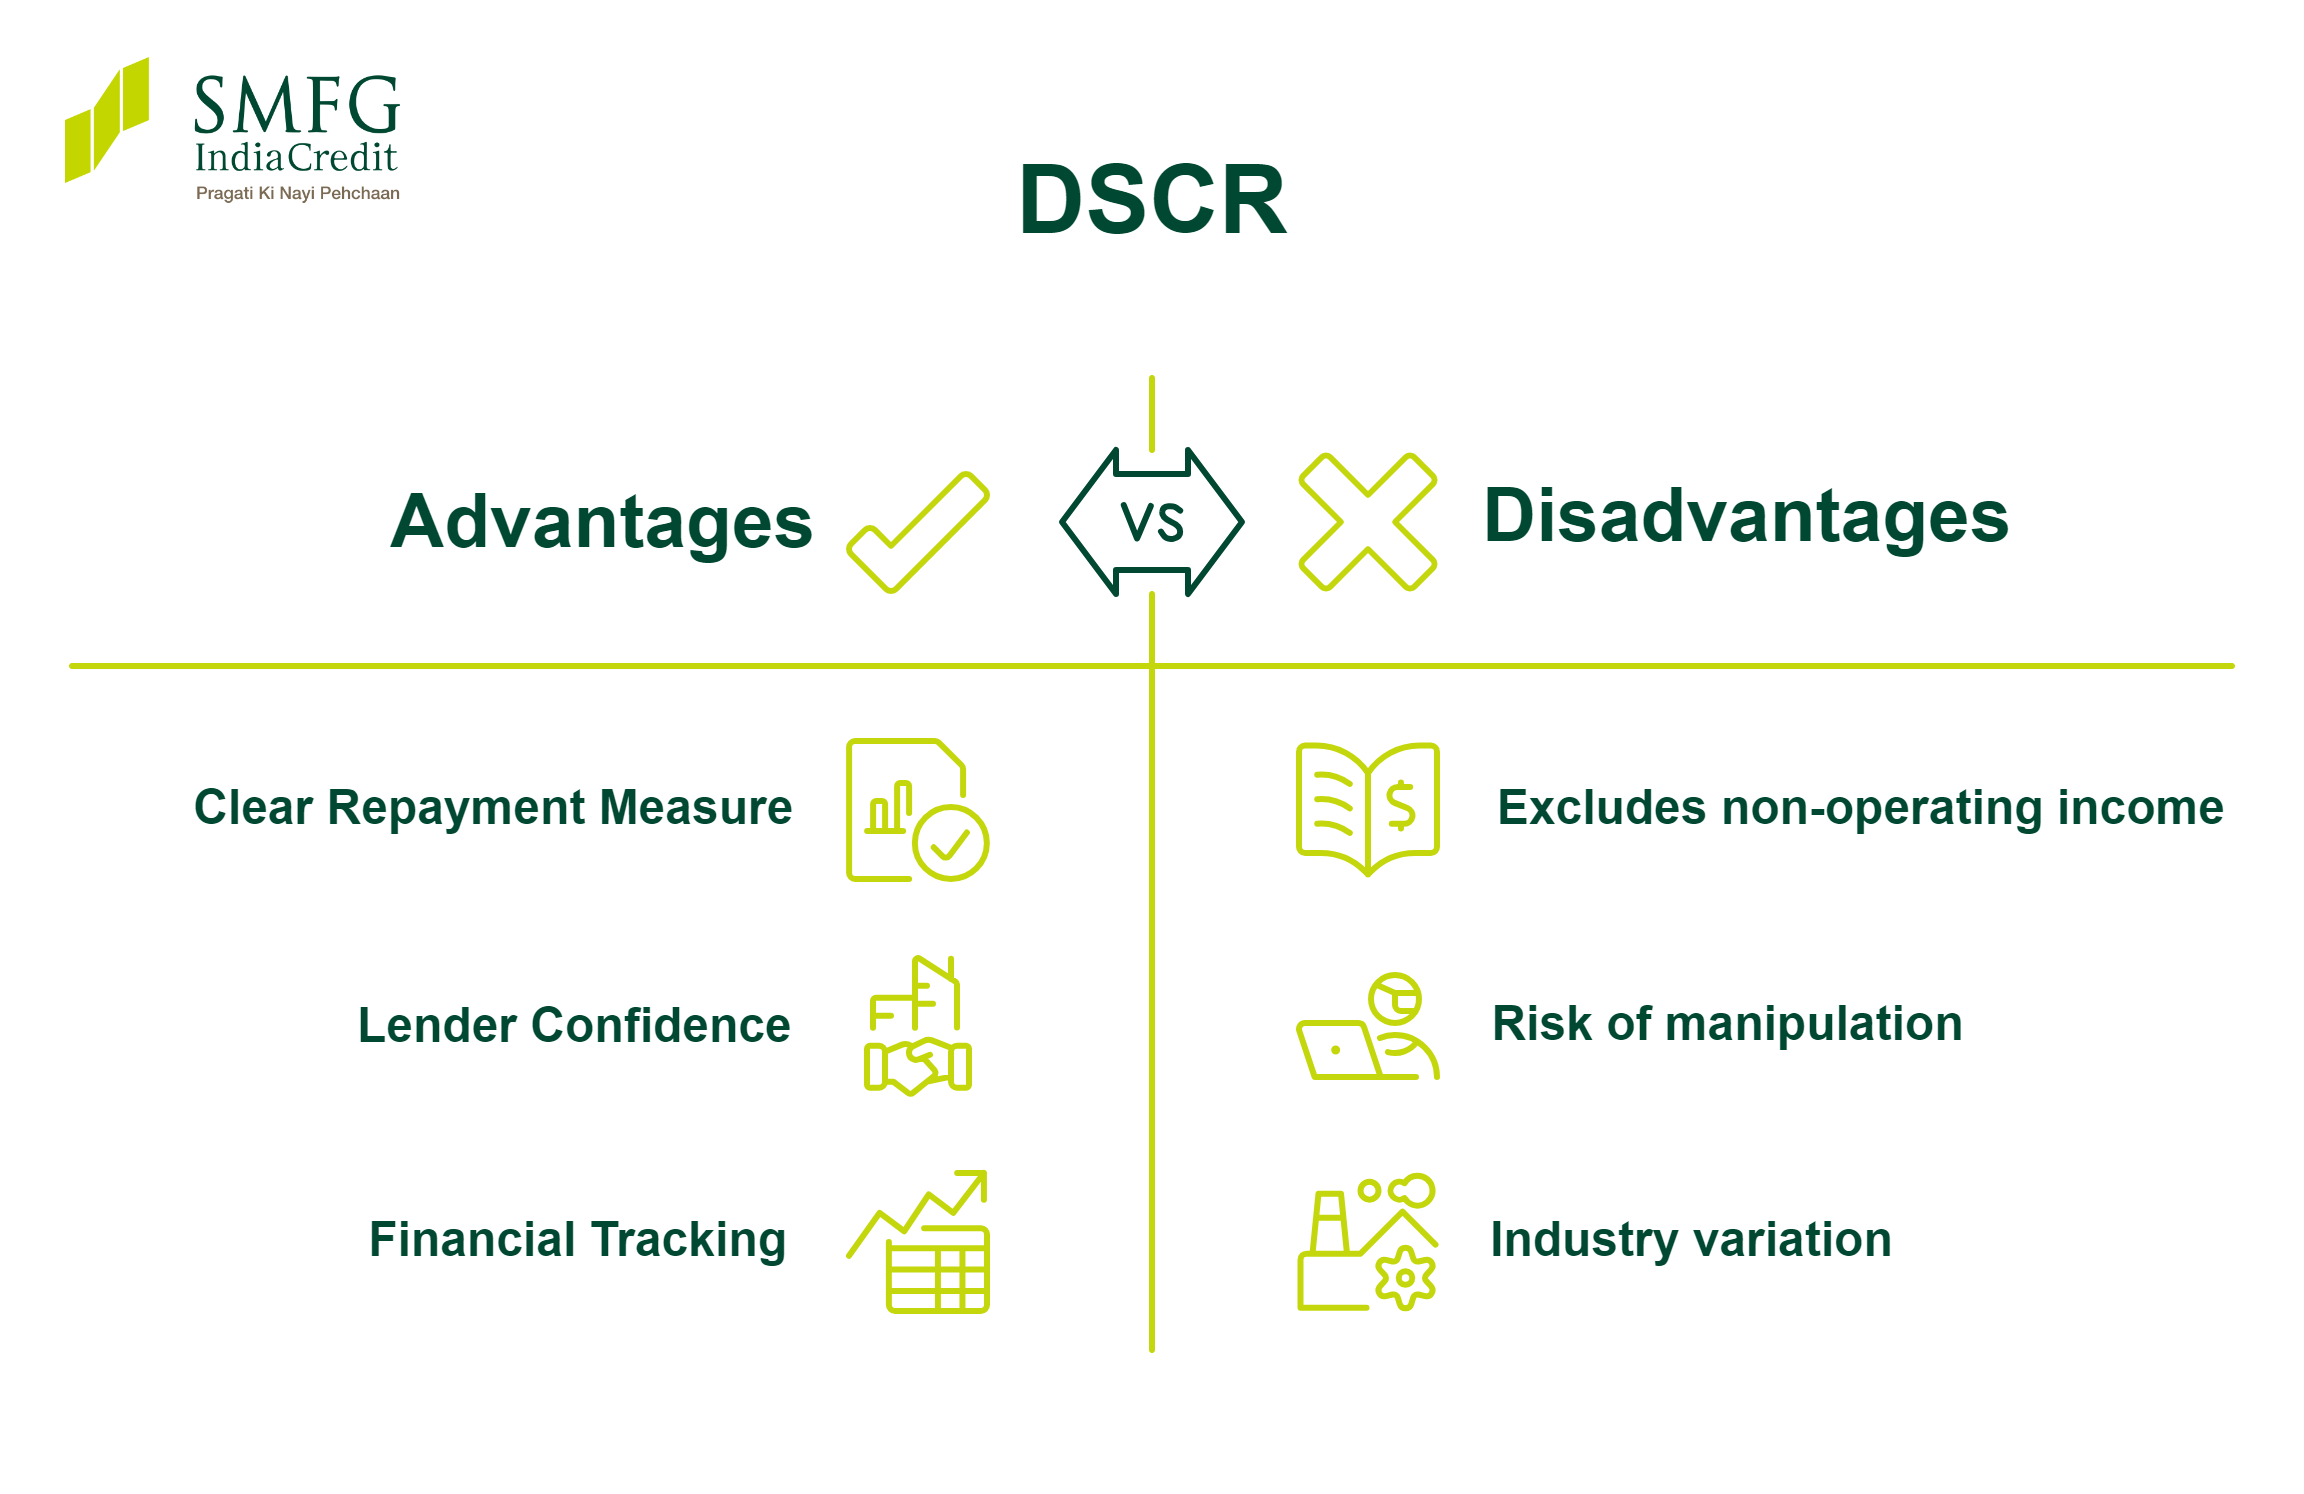
Advantages:
- Provides a clear measure of repayment capacity.
- Boosts lender confidence in business loan approvals.
- Helps track financial health for long-term planning.
Disadvantages:
- Excludes non-operating income like asset sales or grants.
- Risks the manipulation of financial data by creative accounting.
- Varies by industry, needing tailored analysis for accuracy and relevance.
Common Mistakes While Calculating DSCR
Businesses should avoid these common mistakes:
- Using total revenue instead of Net Operating Income (NOI).
- Ignoring principal repayments when calculating Total Debt Service.
- Including one-time or non-recurring income that does not reflect normal business performance.
- Excluding existing debt repayment obligations.
- Mixing monthly figures with annual figures in the same calculation.
- Overlooking changes in operating expenses or working capital.
- Using unrealistic financial projections when estimating future repayment capacity.
DSCR Formula for Real Estate/Rental Income Loans
The DSCR formula is also commonly used for commercial real estate and rental income-based lending. In such cases, lenders typically compare a property's Net Operating Income (NOI) with its annual Total Debt Service to determine whether rental income is sufficient to cover loan repayments.
Formula:
DSCR = Property Net Operating Income ÷ Annual Total Debt Service
A higher DSCR generally indicates that the property generates enough rental income to comfortably meet its debt obligations. However, lenders may also consider occupancy levels, property expenses and rental income stability when evaluating loan applications.
Conclusion
The DSCR is one of the vital financial metrics for businesses seeking loans and ensuring long-term stability. Regular monitoring of DSCR helps identify potential financial risks early, allowing companies to take proactive measures to maintain healthy debt levels. By understanding and managing this ratio effectively, businesses can improve their chances of securing loan approvals on favourable terms.
For enterprises looking to expand or manage cash flow effectively, SMFG India Credit offers unsecured business loans of up to Rs. 1 Crore*. Estimate the maximum amount you may be able to borrow using our business loan eligibility calculator and apply online today to benefit from competitive interest rates.