The processing fee for a personal loan is a one-time charge that lenders levy to cover the administrative costs involved in processing and assessing your application. It is separate from the interest charged on the loan and may be deducted from the sanctioned amount before disbursal or collected separately, depending on the lender's policy.
This article explains what a personal loan processing fee is, why lenders charge it, how it is calculated, and what you should check before applying.
Why Do Lenders Charge a Processing Fee?
A processing fee covers the lender service charges involved in reviewing your application, verifying documents, checking your credit score (CIBIL), and running background checks before approval. It is one of the common personal loan charges that borrowers should consider when comparing loan offers.
Understanding the processing fee in a loan, along with other applicable fees and charges, can also help you assess the overall borrowing cost more accurately. It is not a penalty, and lenders need to clearly disclose it as part of the applicable schedule of charges.
Is the Processing Fee Refundable?
In most cases, the processing fee for a personal loan is non-refundable once it has been charged, as it covers the administrative work involved in processing the application. However, refund policies can differ between lenders and may also depend on the stage at which the application is withdrawn, rejected, or cancelled.
Since personal loan processing charges and their refund conditions vary, check the applicable terms and the loan agreement carefully to understand when the fee is charged and whether any refund provisions apply.
How Is the Personal Loan Processing Fee Calculated?
Loan processing fees are usually calculated as a percentage of the sanctioned loan amount, with applicable Goods and Services Tax (GST) charged separately. The exact processing fee percentage varies depending on the lender's policies and the applicable loan terms.
|
Loan Amount
|
Processing Fees of a Personal Loan (%)
|
Fee Before GST
|
GST (18%)
|
Total Charge
|
|
Rs. 2,00,000
|
2%
|
Rs. 4,000
|
Rs. 720
|
Rs. 4,720
|
|
Rs. 5,00,000
|
3%
|
Rs. 15,000
|
Rs. 2,700
|
Rs. 17,700
|
|
Rs. 10,00,000
|
3.5%
|
Rs. 35,000
|
Rs. 6,300
|
Rs. 41,300
|
Note: The above figures are for illustrative purposes only. Actual processing fees may vary depending on the lender, loan product, and applicable terms.
Formula for Processing Fee Calculation
The basic formula is:
Processing Fee = Loan Amount × Processing Fee Percentage
Applicable GST is then calculated separately on the processing fee.
Example of Processing Fee Calculation
Suppose you take a personal loan of Rs. 4,00,000 and the lender charges a 4% loan application processing fee. The base fee would be Rs. 16,000. After adding 18% GST of Rs. 2,880, the total charge would come to Rs. 18,880.
Factors That Affect Personal Loan Processing Fees
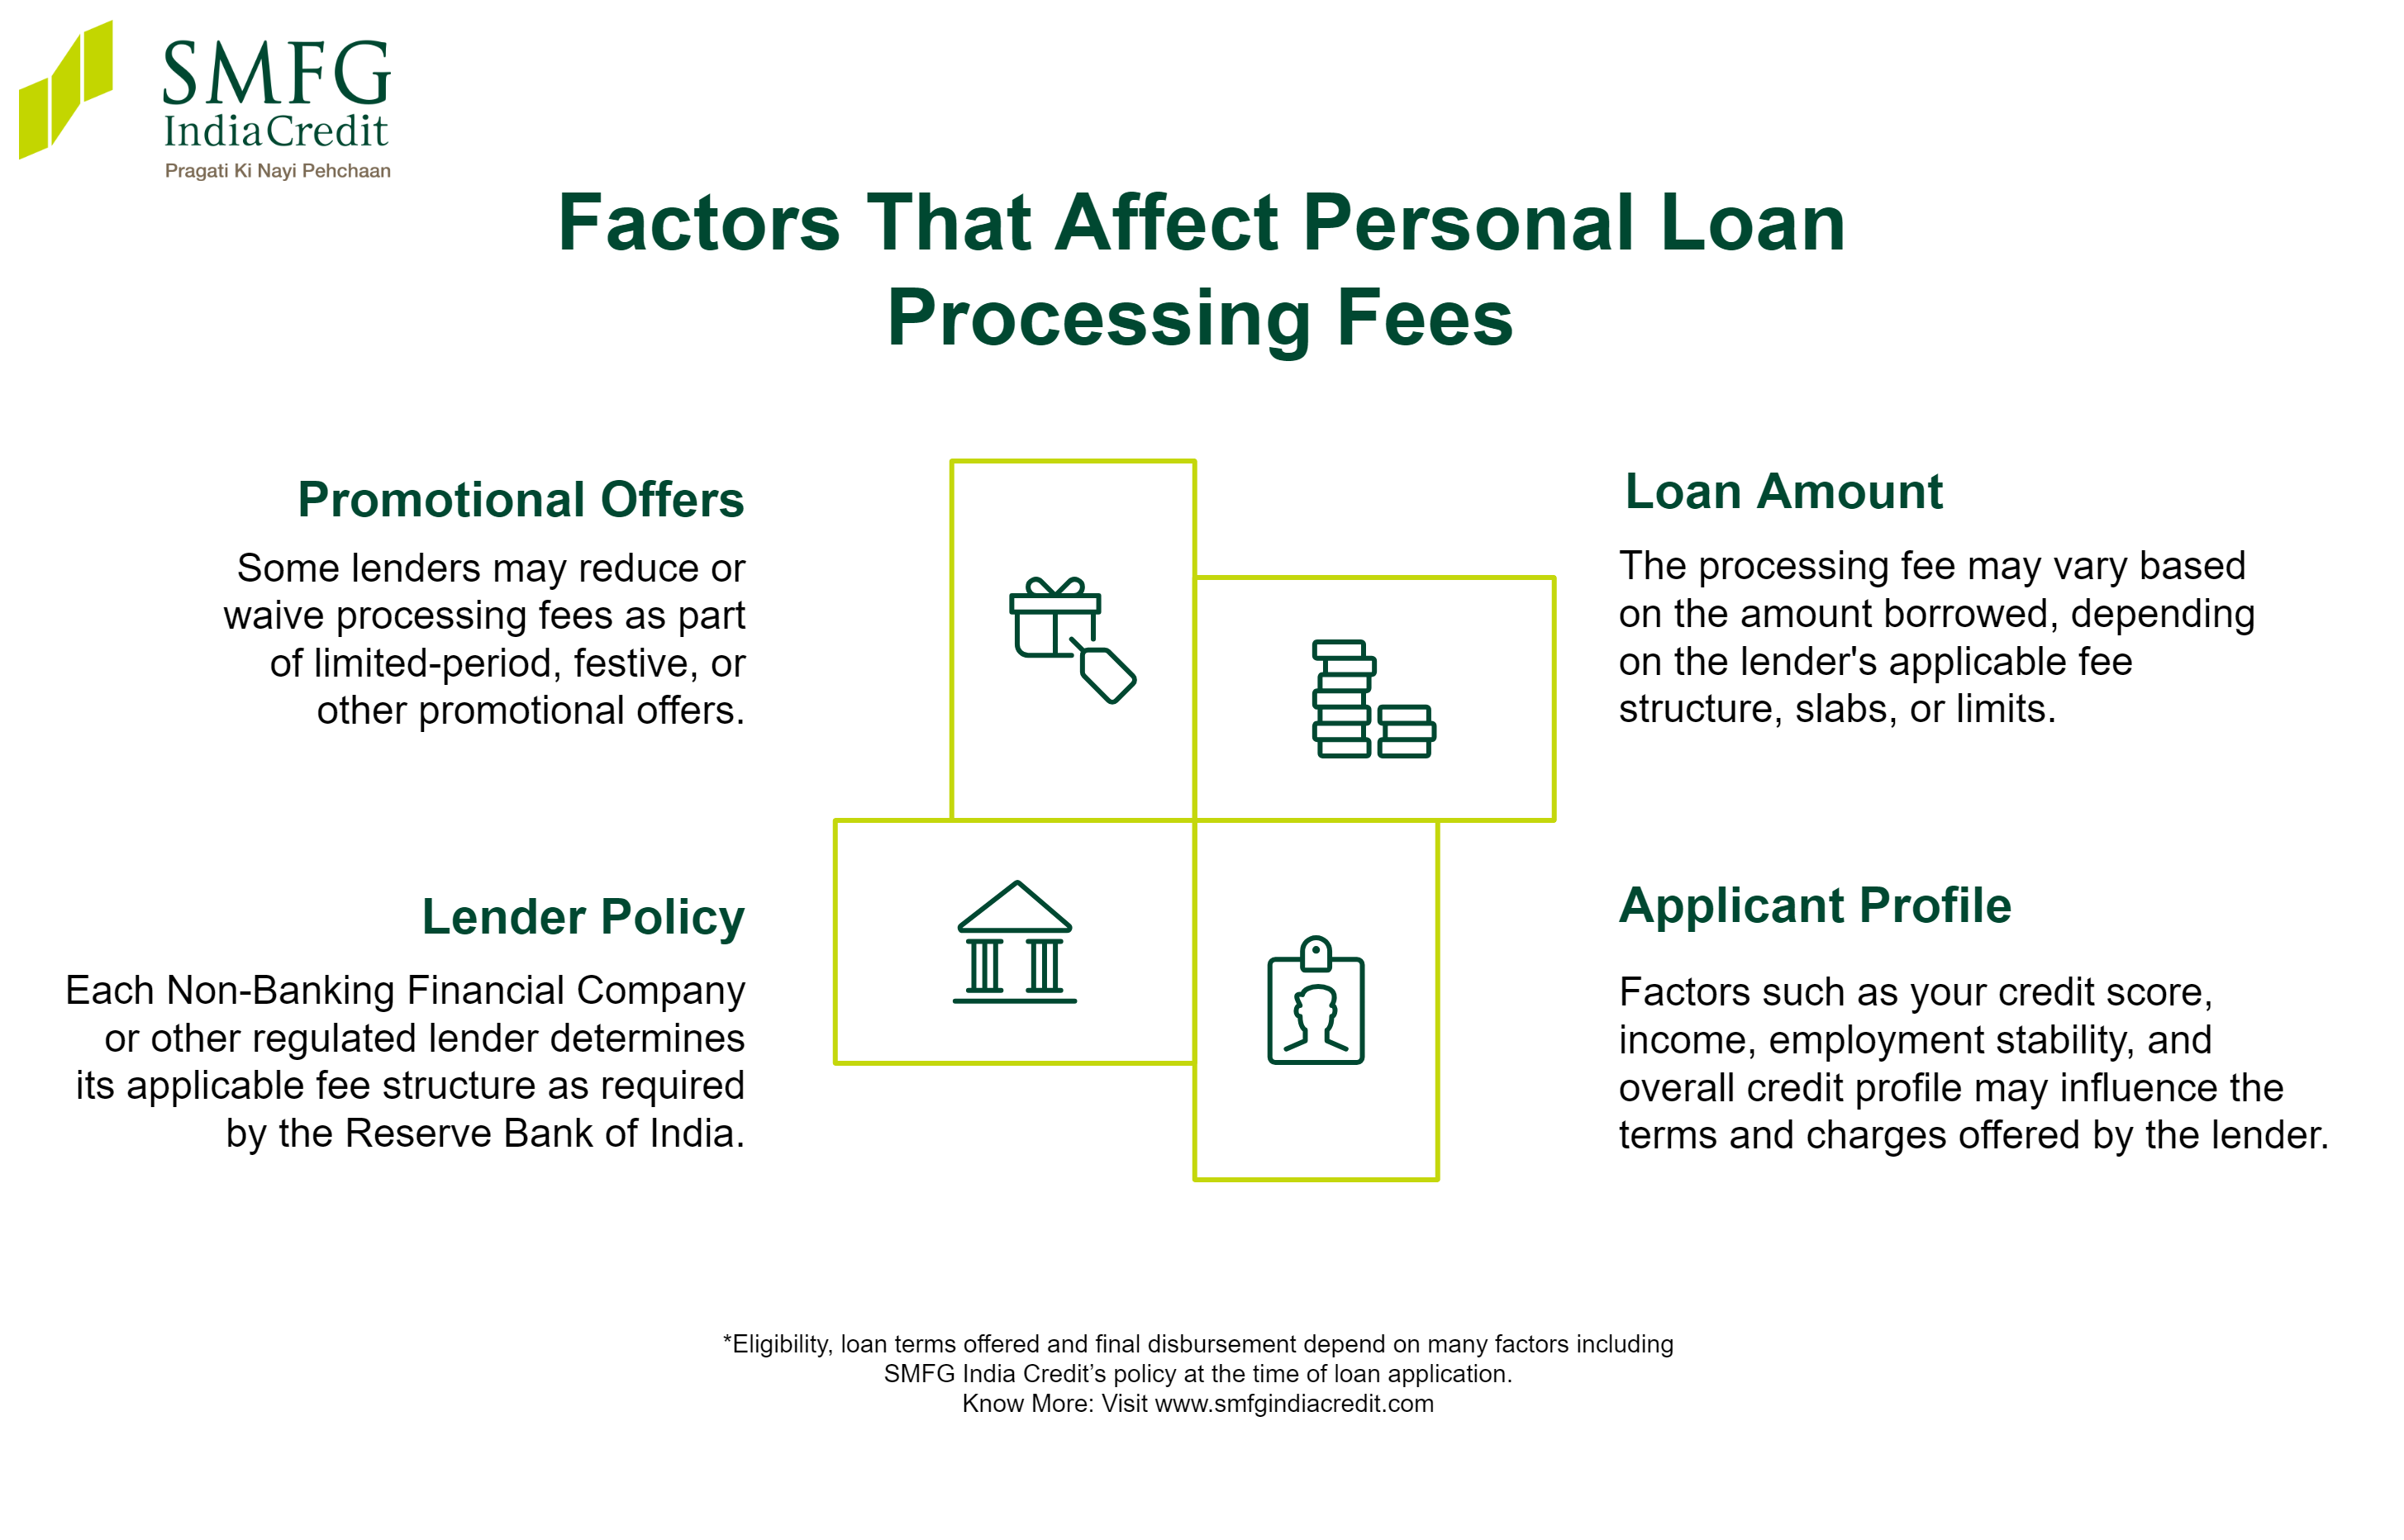
Several factors can influence the processing fees for personal loan offers:
- Loan Amount: The processing fee may vary based on the amount borrowed, depending on the lender's applicable fee structure, slabs, or limits.
- Applicant Profile: Factors such as your credit score, income, employment stability, and overall credit profile may influence the terms and charges offered by the lender.
- Lender Policy: Each Non-Banking Financial Company (NBFC) or other regulated lender determines its applicable fee structure. The Reserve Bank of India (RBI) requires regulated lenders to transparently disclose applicable fees and charges to borrowers.
- Promotional Offers: Some lenders may reduce or waive processing fees as part of limited-period, festive, or other promotional offers.
Processing Fee vs Interest Rate
The processing fee and interest rate both contribute to the total cost of a personal loan, but they are charged differently. Understanding the distinction can help you assess a loan offer more accurately before signing the agreement.
|
Aspect
|
Processing Fee
|
Interest Rate
|
|
Nature
|
One-time charge for processing the loan application
|
Cost of borrowing the loan amount
|
|
How it is charged
|
Generally calculated as a percentage of the loan amount
|
Applied to the outstanding loan amount
|
|
Payment
|
Charged or deducted as per the lender's applicable terms
|
Repaid as part of the Equated Monthly Instalment (EMI)
|
|
Impact on cost
|
Adds to the upfront or initial cost of borrowing
|
Influences the EMI and total interest payable over the loan tenure
|
Comparing all applicable fees and charges alongside your personal loan interest rates gives you a clearer understanding of the overall cost of borrowing.
Other Charges Associated With a Personal Loan
Beyond the processing fee, personal loan fees and charges may include several other costs depending on the lender's terms and how the loan is managed:
|
Charge Type
|
When It Applies
|
|
Prepayment Charges
|
When part of the outstanding loan amount is repaid before its scheduled due date
|
|
Foreclosure Charges
|
When the entire outstanding loan amount is repaid before the end of the agreed tenure
|
|
Late Payment Charges
|
When an EMI or other amount due is not paid by the applicable due date
|
|
Payment/EMI Bounce Charges
|
When an EMI payment fails or is dishonoured
|
|
Loan Cancellation Charges
|
When a loan is cancelled after sanction or disbursal, subject to the lender's applicable terms
|
These charges are separate from personal loan processing charges and generally arise only when the relevant event occurs. The types of charges, amounts, and conditions can vary between lenders.
Can You Reduce or Avoid a Processing Fee?
While a processing fee of a personal loan is part of a lender's standard charges, you can explore ways to reduce the amount you pay:
- Compare processing fees, interest rates, and other applicable charges across different lenders before making a decision.
- Check whether lenders are running limited-period or promotional offers that reduce or waive processing fees for eligible applicants.
- Ask the lender whether any fee concessions are available based on your eligibility, credit score strength, or existing relationship with them.
- Review the applicable terms carefully to confirm the processing fee, taxes, and other charges before accepting the loan.
Note that fee reductions or waivers are subject to the lender's policies and are not guaranteed.
What Is the SMFG India Credit Personal Loan Processing Fee?
The SMFG India Credit personal loan processing fee is Up to 4% of the total loan amount + GST. The table below provides an overview of the processing fee and other key charges associated with the loan:
|
Fees and Charges
|
Amount Chargeable
|
|
Personal Loan Interest Rate
|
Starting at 12.5%* per annum
|
|
Processing Fee
|
Up to 4% of the total loan amount + GST
|
|
Late Payment Charges
|
2% per month (24% per annum) on overdue amount calculated on a day-to-day basis, payable from the relevant due date till the date of actual payment
|
|
Cheque/ECS/NACH Dishonour Charges (per dishonour of cheque/ECS/NACH per presentation)
|
Rs. 500 + GST
|
|
Loan Cancellation Charges (loan cancelled before the first EMI)
|
Rs. 1,000 + GST
|
|
Loan Tenure
|
Up to 60 months
|
Things to Check Before Paying the Processing Fee
Before paying a one-time processing fee, review the applicable charges and loan terms carefully so you know what you will pay and under what conditions.
- Check the processing fee percentage and calculate the actual amount payable based on your loan amount.
- Confirm whether GST applies over and above the quoted processing fee and account for it when estimating the final charge.
- Review the lender's refund policy, particularly the conditions applicable if your application is withdrawn, rejected, or cancelled.
- Read the loan terms to understand when the fee becomes payable and whether it is deducted during loan disbursement or collected separately.
- Consider the Annual Percentage Rate (APR), where provided, along with the interest rate and applicable charges to assess the overall cost of borrowing.
Use a personal loan EMI calculator to estimate your monthly repayment for the loan amount, interest rate, and tenure you are considering. You can then assess the EMI alongside the processing fee and other applicable charges for a clearer view of the overall borrowing cost.
Conclusion
The processing fee for a personal loan is an important cost to consider when evaluating a loan offer. Usually calculated as a percentage of the loan amount with applicable GST added separately, it covers the lender's administrative costs for processing the application. Checking this fee alongside the interest rate and other applicable charges can give you a better understanding of the overall borrowing cost.
If you are considering a personal loan, SMFG India Credit offers funds of up to Rs. 10 Lakhs* at competitive interest rates starting from 12.5%* per annum and nominal processing fees of Up to 4% of the total loan amount + GST. You can use the personal loan eligibility calculator to get an initial estimate of the loan amount you may be eligible for based on your financial profile.
Before applying, review the personal loan documents required and keep the applicable paperwork ready. Once you have checked the eligibility criteria, along with the applicable fees and charges, apply for an SMFG India Credit personal loan online.