An updated income tax return, filed using Form ITR-U under Section 139(8A) of the Income Tax Act, 1961, lets you correct errors or report missed income from previous years. You can file it within 48 months from the end of the relevant assessment year. An additional tax between 25% and 70% applies depending on how late you file.
What Is an Updated Return Under Section 139(8A)?
Section 139(8A) of the Income Tax Act allows any taxpayer to file an updated income tax return (ITR-U) to correct errors or report missed income in a previously filed return. The provision was introduced to encourage voluntary compliance.
Unlike a revised return, it can be filed even after the window for revised and belated returns has closed. The ITR 139(8A) provision covers individuals, HUFs, firms, LLPs, companies, and other entities. It can only be used to increase tax liability, not to reduce it or claim a refund.
Who Can File an Updated Return Under Section 139(8A)?
ITR-U eligibility is broad. Any taxpayer who has made an error or omission in any of the following returns can proceed with an ITR-U filing:
- Original return filed under Section 139(1)
- Belated return filed under Section 139(4)
- Revised return filed under Section 139(5)
- No return filed at all (missed the original, belated, and revised deadlines entirely)
The specific situations where updated income tax return filing is allowed include:
- Income that was not declared or was incorrectly declared
- Selection of the wrong head of income
- Tax paid at the wrong rate
- Reduction of carried-forward losses to be corrected
- Reduction of unabsorbed depreciation to be corrected
- Reduction of tax credits under Sections 115JB or 115JC
Who Cannot File an Updated Return?
Updated return income tax cannot be filed when:
- It results in lower tax or a higher refund
- An updated return was already filed for the same year
- Search, survey, or seizure proceedings have been initiated
- Assessment or reassessment is pending or completed
- The return is a NIL return or a loss return
Time Limit for Filing Updated Return Under Section 139(8A)
The ITR-U time limit is 48 months from the end of the relevant assessment year.
|
Financial Year
|
Assessment Year
|
Last Date to File ITR-U
|
|
FY 2020-21
|
AY 2021-22
|
31 March 2026
|
|
FY 2021-22
|
AY 2022-23
|
31 March 2027
|
|
FY 2022-23
|
AY 2023-24
|
31 March 2028
|
|
FY 2023-24
|
AY 2024-25
|
31 March 2029
|
|
FY 2024-25
|
AY 2025-26
|
31 March 2030
|
Taxpayers can file ITR-U only after the end of the relevant assessment year.
If filing an updated return results in additional tax liability, it is important to plan your finances carefully, especially if you’re also considering borrowing. In such situations, tools like a personal loan EMI calculator can help estimate monthly repayment obligations alongside other financial commitments.
Benefits of Filing an Updated Return (ITR-U)
Filing an updated ITR through ITR-U has several practical advantages:
- Correcting missed or incorrectly reported income
- Reducing the risk of notices, scrutiny, and litigation
- Maintaining a cleaner tax record, which may support applications for personal loan, visas, and other financial transactions
- Getting a longer four-year window to update previously filed returns
Additional Tax Liability Under Section 139(8A)
Filing an updated income tax return under Section 139(8A) requires taxpayers to pay additional tax along with the applicable interest.
|
Time of Filing ITR-U
|
Additional Tax Payable
|
|
Within 12 months
|
25% of tax and interest
|
|
Within 24 months
|
50% of tax and interest
|
|
Within 36 months
|
60% of tax and interest
|
|
Within 48 months
|
70% of tax and interest
|
The additional tax amount increases as the filing is delayed, making it beneficial to update returns at the earliest opportunity.
If you’re planning for these liabilities alongside any borrowing needs, it is prudent to include tools like a personal loan eligibility calculator to assess your repayment capacity before applying for credit.
How to File an ITR Updated Return?
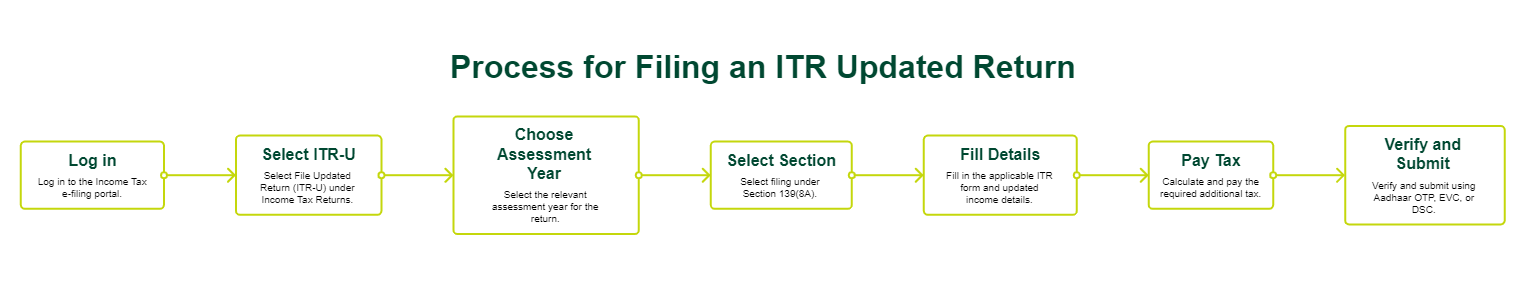
Updated ITR filing can be done through the Income Tax e-filing portal. Here is the process:
- Log in to the Income Tax Portal.
- Select “File Updated Return (ITR-U)” under Income Tax Returns.
- Choose the relevant assessment year.
- Select filing under Section 139(8A).
- Fill in the applicable ITR form and updated income details.
- Calculate and pay additional tax.
- Verify and submit the return using Aadhaar OTP, EVC, or DSC.
Documents Required for Filing ITR-U
Keep the following ready before you begin your updated return income tax filing:
- PAN card and Aadhaar card
- Original return acknowledgement details (if filed earlier)
- Form 26AS, Annual Information Statement (AIS), and Taxpayer Information Summary (TIS)
- Bank and income statements
- Proof of additional income and taxes paid
- Challan details for tax paid under Section 140B
Revised Return vs Updated Return: Key Differences
|
Parameter
|
Revised Return (Section 139(5))
|
Updated Return (Section 139(8A))
|
|
Purpose
|
Correct any errors in the original return
|
Report missed income or correct under-reporting
|
|
Time limit
|
Before 31 December of the relevant AY or prior to the completion of assessment by the tax authorities, whichever occurs earlier
|
Up to 48 months from the end of the assessment year
|
|
Can reduce tax liability
|
Yes
|
No
|
|
Can claim or increase refund
|
Yes
|
No
|
|
Can be filed if no original return was filed
|
No
|
Yes
|
|
Additional tax payable
|
No
|
Yes (25% to 70%)
|
|
Can be revised again after filing
|
Yes (within time limit)
|
No (only one per AY)
|
|
Applicable after assessment
|
No
|
No (unless after reassessment proceedings with 10% extra tax as per Budget 2026)
|
Common Reasons for Filing an Updated Return
These are the situations that most commonly lead taxpayers to file an updated ITR filing:
- Interest income from fixed deposits or savings accounts that was omitted
- Freelance or professional income not reported in the original return
- Capital gains from mutual funds or shares that were missed
- Income from a second property or rental income not declared
- Incorrect head of income used (for example, professional income reported as salary)
- Foreign income or assets not disclosed in the original return
- Tax deducted at source is not reconciled with the actual income
Common Mistakes to Avoid While Filing an Updated Return
- Filing ITR-U to reduce tax liability, which is not allowed
- Not paying additional tax before submission
- Selecting the wrong ITR form after updating income details
- Delaying filing and increasing additional tax liability
- Ignoring the impact on subsequent years’ losses or depreciation
Latest Updates Related to Section 139(8A) for FY 2026
As per the Budget 2026 proposals, in order to reduce litigations, taxpayers can file an updated return even after the initiation of reassessment proceedings by paying an additional 10% tax over and above the existing additional taxes applicable on updated returns. During reassessment proceedings, the assessing officer may refer only to the updated returns filed. Further, with effect from 1 March 2026, taxpayers may also be allowed to file updated returns for the reduction of losses.
Taxpayers should also keep an eye on notifications and circulars issued by the Central Board of Direct Taxes for the latest rules, clarifications, and implementation updates related to these proposals.
Conclusion
Section 139(8A) of the Income Tax Act allows taxpayers to correct missed or incorrect income tax filings through ITR-U within a four-year window. Filing early helps reduce additional tax liability and lowers the risk of notices or scrutiny.
As you plan for your goals, alongside tax obligations and regular expenses, SMFG India Credit can support you with unsecured funds of up to Rs. 10 Lakhs* at personal loan interest rates starting from just 12.5%* per annum.
Check your eligibility and apply online today with minimal personal loan documents.
* Please note that this article is for your knowledge only. Loans are disbursed at the sole discretion of SMFG India Credit. Final approval, loan terms, disbursal process, foreclosure charges and foreclosure process will be subject to SMFG India Credit's policy at the time of loan application. If you wish to know more about our products and services, please contact us